
Marketing a Sporting Operation in Georgia: The Full State Guide
Updated: Oct 21

Georgia's operators look healthy on paper. In our 2026-27 audit of 136 Georgia operators, the mean digital health score was 5.37 out of 10, a little above the 5.09 mean across the 1,546 verified operators in 11 states. That number reads like a win. Then the sub-regions open it up. The North Georgia Mountains averaged 5.88 and the Piedmont and Central Georgia 5.69, while the Plantation Belt in the southwest averaged 4.58, with about half of the 24 operators we audited there scoring 4 or below. The state average hides very different markets, and the rest of this guide takes them one at a time.
What separates those markets is how well each operator is set up to be found and chosen. Across Georgia, 87 percent of the operators we audited had their own website, and of the 109 sites we could read, 71 percent carried some structured data. But only 35 percent showed FAQ content and just 2 percent used FAQPage schema. On the coast, 50 percent of the Golden Isles sites we read showed FAQ content, against 29 percent in the Savannah sub-region. Booking platforms, state tourism boards and national content networks fill the gaps wherever individual operators have not published specific, local, experience-forward content.
The Georgia Sporting Landscape: A State of Contrasts
Georgia's sporting geography creates natural market segmentation that most operators have yet to learn to exploit. The state runs from the Blue Ridge escarpment in the north -- where cold-water trout streams, bear hunts, and mountain turkey country attract a different client profile than anything in the coastal plain -- through the red clay Piedmont, down into the longleaf savanna and plantation quail country of the south, and finally to the tidal marshes, barrier islands, and offshore blue water of the coast. Each zone has distinct seasonality, species assemblages, and client psychographics. A Salt Marsh Estuary client booking a January redfish trip out of Savannah is not the same person booking a December quail hunt on a Baker County plantation, and neither resembles the drift-boat fly angler planning a May trip to the Toccoa below Blue Ridge Dam.
The competitive implication: operators who build content that speaks to zone-specific client psychology will rank for terms that booking platforms and directories cannot, because those platforms are generalists by design. A platform has a Georgia page. It does not have a page optimized for the specific experience of wading the Chattahoochee tailwater in October for trout while fall color peaks in the hardwood canopy above you. That experience is ownable. The operator who describes it in precise, specific, sensory language - and structures that description so search engines and AI systems can parse it - will own it.
Zone-by-Zone Digital Audit
Blue Ridge Mountains and North Georgia Trout Country
The Chattahoochee headwaters, Toccoa River, Conasauga, Jacks River, and the scattered wild trout streams of the Blue Ridge WMA represent Georgia's most technically demanding fisheries and a digital content market with room for more specific coverage. The Georgia DNR stocks heavily throughout this region, which creates a large volume of casual angler searches -- "trout fishing near Blue Ridge GA," "stocked trout streams north Georgia" -- that are genuinely competitive and dominated by DNR pages, tourism boards, and content farms. But the quality fly-fishing market -- anglers specifically seeking guided wade trips on technical water, streamer fishing in high flows, or technical dry-fly fishing during sulfur hatches -- appears to be far less contested in organic search.
The Toccoa tailwater below Blue Ridge Dam is an obvious content opportunity. This is a well-regarded trout fishery with relatively consistent flows, rainbow and brown trout, and the kind of technical fishing that produces passionate repeat clients. There are licensed guides operating on this water, and the North Georgia Mountains sub-region was the strongest in our audit: its 26 operators averaged 5.88, 96 percent had their own site, and 40 percent of the 25 sites we read showed FAQ content. Even so, the tailwater's own story - flow schedules, hatch charts, fly selection by season, access point logistics, what gear to bring - is an area where an operator can still publish the definitive version.
The Cohutta Wilderness and its tributary streams - including upper sections of the Conasauga and Jacks River - represent some of the most demanding and rewarding wild trout fishing in the state. These streams hold populations of wild rainbow and brown trout in roadless terrain requiring significant hiking. The angler who seeks this experience is highly motivated, research-intensive, and poorly served by general listing sites. A guide or outfitter who built a comprehensive content hub around Cohutta Wilderness fishing - trail distances, stream conditions by season, tackle considerations for tight canopy and pocket water - would face little direct competition from aggregators, who have no incentive to produce this level of specificity. Because the Cohutta is federal wilderness, any guided trip depends on the permits and rules that apply there, so check them with the U.S. Forest Service before promoting trips.
Piedmont Bass Fisheries and Shoal Bass Country
Georgia holds a core part of the native range of the shoal bass, a species found in flowing-water environments in the Chattahoochee, Flint, and their major tributaries. The shoal bass has developed a devoted following among fly anglers and light-tackle enthusiasts who specifically seek it out - a niche with national reach and high client value. Operator-owned content for this market is relatively sparse, and search results for "shoal bass fishing guide Georgia" and "Flint River shoal bass" lean heavily on academic papers, forum threads, and state agency reports. An outfitter who built genuine expertise content around shoal bass - their behavior, habitat preferences, optimal tackle, seasonal patterns, access considerations on the Flint versus the lower Chattahoochee - would be well placed to serve a national niche.
The Chattahoochee through metro Atlanta - particularly the float section from Buford Dam down through Roswell, Marietta, and the city reaches - represents a high-volume market with different competitive dynamics. Here, the sheer population density creates strong search demand for "Chattahoochee fishing guide," "Atlanta fly fishing," and related terms. Multiple operators compete for this traffic, and the competition is more mature. However, even here, there are gaps: the shoal sections below the city, the trout water below Buford Dam, and the spotted bass fishery in the lower Piedmont reaches. Urban anglers are poorly served by content that goes beyond the top five stockpile spots.
South Georgia Plantation Belt and Quail Country
The traditional plantation quail country of South Georgia - centered on Thomasville but extending across Baker, Mitchell, Grady, Thomas, and adjacent counties - represents one of the most valuable sporting real estate markets in the Southeast. Plantation operations here command premium rates, and the client demographic skews toward high-net-worth individuals with sophisticated expectations. The Plantation Belt is also where the audit shows the most room to grow. Of the 24 operators we audited in that sub-region, 21 are upland, plantation or sporting clays operations; their mean digital health score was 4.58, the lowest of Georgia's six sub-regions, 45 percent of the 18 sites we read showed a copyright year of 2023 or older, and 22 percent offered a newsletter signup. A handful of plantation operations have invested in genuine brand presence, with professional photography and editorial content that align with their physical products. Many rely on word-of-mouth networks that are increasingly leaky as demographics shift and new money enters the market, without the inherited social connections that historically drove referrals.
The specific gap in plantation quail country is not rankings for "quail hunting Georgia" -- that term is reasonably competitive, and most established operations appear for it. The gap is in the supporting content ecosystem: the explainers about what a traditional Georgia quail hunt actually looks like, how the dog work differs from western shooting preserve hunting, what a first-time quail hunter should expect in terms of pace, terrain, and protocol, how to select between operations at different price points, and what the season structure looks like across the October-March window. This educational content would serve both the first-time high-value client who is researching an experience he has never had and the AI answer boxes that are beginning to dominate planning queries in the luxury outdoor market.
Deer hunting in South Georgia - particularly management-quality whitetail on agricultural and mixed-timber properties - is a different market with higher volume and lower average client value. The best operations are running quality deer management programs on large acreages and producing consistent mature buck harvests. For those operations, content that shows the management program, the acreage and the harvest standards is the most direct way to reach the buyer. The client segment they are targeting - serious trophy hunters willing to pay for managed properties with significant antler genetics - is research-intensive and increasingly likely to first encounter an operation through content rather than referral.
Coastal Georgia: The Marshes, Inlets, and Offshore
The Georgia coast operates in the shadow of the Florida and South Carolina charter markets and has consequently developed an inferiority complex in its marketing. This is misplaced. Georgia's salt marsh system, one of the most extensive on the East Coast, offers excellent redfish and trout fishing in the low-country tidal creeks, combined with strong inshore and nearshore species diversity, including flounder, cobia, tarpon (seasonal), tripletail, and sheepshead. The offshore fishery out of Brunswick and St. Simons Island, while requiring a longer run than Florida alternatives, reaches the same Gulf Stream waters and can produce billfish, tuna, and mahi fishing.
The digital gap on the Georgia coast is partly geographic and partly species-specific. The audit gives a hint on the geographic side: 50 percent of the Golden Isles sites we read showed FAQ content against 29 percent in Savannah, and none of the sites read in either sub-region used FAQPage schema. Redfish content for the Georgia coast is reasonably developed. Content for the tarpon migration through Georgia inlets - a summer and early fall event, peaking from mid-July into October - appears far less often in operator-owned pages, and tripletail, which would attract a devoted national niche, and the sheepshead fishery around the Georgia jetties and structure, which many anglers rate highly, tend to get little dedicated editorial treatment.
Cumberland Island represents a unique case: exceptional historic and ecological context combined with a wilderness setting creates a high-value content opportunity. The island is a national seashore, reached by ferry, with no public roads and documented historic structures, so any activity there is governed by National Park Service rules. Check the current NPS regulations and permit requirements before promoting any hunting, fishing or guided activity on the island. Well-photographed, well-written coverage of the island's history, wildlife and surf fishing can attract an engaged audience, as long as it stays within what is permitted.
The Aggregator Problem in Detail
Booking platforms and directories illustrate how aggregator interception works at scale. Large platforms index guide listings for many charter and guide operations in the state, build location pages for significant fisheries, and accumulate review content that can outrank an operator's own website for its services. The mechanism is not complicated: they invest in technical SEO, domain authority, review volume, and content breadth at a scale no individual operator can match. The result is that a client searching "Savannah inshore fishing guide" may be more likely to land on a listing page - where they will be presented with multiple operators and little reason to develop brand loyalty to any of them - than on an individual operator's website.
The counter-strategy is not to compete with those platforms on their terms. It is to build content that a platform structurally cannot build: highly specific, deeply contextual, experience-forward editorial content that establishes an operator as the authoritative source for a particular type of fishing or hunting in a particular place. A listing page for the Toccoa River is unlikely to include a 2,000-word guide to reading the Toccoa's seams in October when flows are dropping after summer drawdown, and big brown trout are staging for the pre-spawn feed. That content, properly executed and structured, can compete for the specific queries that convert the highest-value clients.
General outdoor content networks represent a different problem: they produce high-volume, low-specificity content optimized for pageviews rather than client conversion. Their Georgia hunting content can rank well for broad terms like "deer hunting Georgia" and "duck hunting Georgia" because they publish constantly and have accumulated domain authority. That content is not designed to send a reader to a specific operator. Operators who understand this distinction - and who recognize that their competition for booking conversions is not those networks but the absence of any compelling reason to contact them specifically - will produce very different content than operators who are simply trying to rank for broad terms.
AI Search and the New Conversion Funnel
The emergence of AI-powered search - Perplexity, Google AI Overviews, Claude, ChatGPT with search - has created a new layer of the discovery funnel that many Georgia outfitters have not yet begun to address. The mechanism differs from traditional SEO: AI systems synthesize answers from multiple sources and present a single response rather than a list of links. For planning queries - "what's the best time of year to fish for redfish in coastal Georgia," "how do I plan a quail hunt in the Thomasville area," "what do I need to know for a Cohutta Wilderness trout trip" - AI systems are increasingly likely to be the first point of contact between a prospective client and the information that shapes their trip planning.
The operator cited in the AI answer is the one whose content is most clearly authoritative, most specifically relevant, and most clearly structured for machine parsing. This is not identical to traditional SEO -- a page that ranks #3 in Google may not be the source an AI system cites -- but the underlying inputs are similar: comprehensive topic coverage, clear factual claims, structured headers and logical organization, genuine expertise signals (specific species, specific techniques, specific locations by name), and content that answers the actual questions planning clients are asking.
The 2026-27 audit did not measure which operators AI systems cite, so we are not publishing citation results. You can check your own position in an afternoon. Run your planning queries (for example "Toccoa River fly fishing guide," "Thomasville quail hunt," "Savannah inshore charter") through a few AI systems and note the sources they cite: agency pages, tourism boards, listing sites or operator pages. Where operator pages are missing from the answers, the opportunity is to publish comprehensive, expert-forward content for that exact question. What the audit did measure is the site-side groundwork: across the Georgia sites we read, 35 percent had FAQ content and 2 percent used FAQPage schema, so there is room to stand out.
Georgia's Outdoor Economy in Numbers
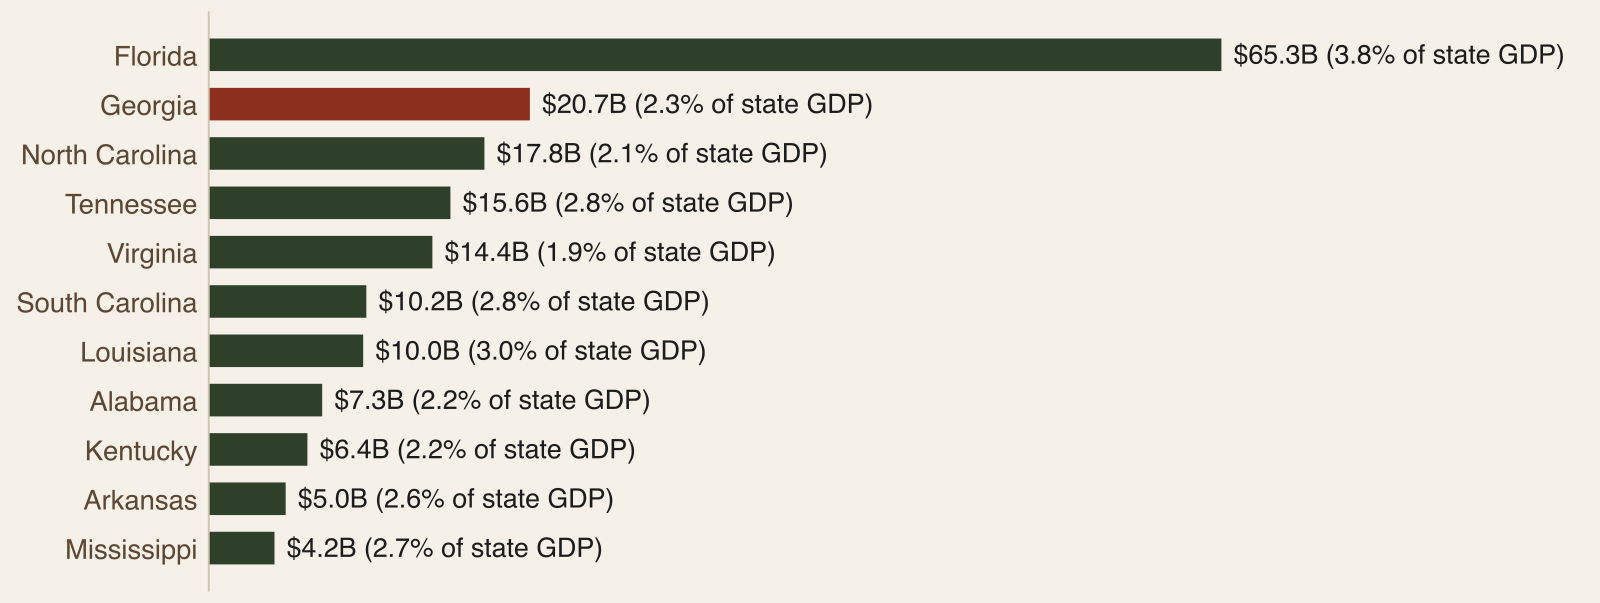
The 2026-27 Georgia Outdoors report puts the state in the region's frame. In its March 2026 release covering 2024, the Bureau of Economic Analysis counts $20.7 billion of outdoor recreation value added in Georgia, 12% of the eleven-state total and the second-largest economy after Florida's $65.3 billion. That was 2.3% of state GDP, below the U.S. figure of 2.4%, and 168,231 jobs, the second-highest count in the region. BEA's 2023 activity table shows where Georgia is strongest: it ranked first in the region in hunting and trapping ($387 million, 21% of the regional total) and second in shooting including archery ($215 million) and in guided tours and outfitted travel of all kinds ($610 million, 12%). Water-based guided tours and charters, the line closest to the guide and charter trade, produced $375 million, third of eleven.
Visitors sit on top. The Georgia Department of Economic Development reported 175.6 million visitors in 2025 who spent $46.2 billion, for a total economic impact of $84.1 billion and 473,837 supported jobs, though the study does not split out outdoor trips and the report never adds it to BEA's figures. Southwick Associates' estimates put angler spending at $4.4 billion in 2022 from 1,114,640 anglers supporting about 38,280 jobs, and hunter spending at $2.00 billion from 819,890 hunters.
Who Buys the Licenses
Georgia is the region's biggest hunting market by license count. It had 815,738 paid hunting license holders in 2024, the highest in the region, up 9.3% from 746,251 in 2020, and 1,129,635 paid fishing license holders, up 6.0% from 1,065,774 and the third-highest count. Against 11.2 million residents, that is 7.3 hunting and 10.1 fishing license holders per 100 people. The nonresident pattern differs by sport. Nonresidents bought 14% of fishing licenses, tags, permits and stamps and paid 22% of fishing license revenue, both among the three lowest shares in the region. In hunting, nonresidents bought only 12% of items but paid 53% of hunting license revenue, $11.2 million against $9.9 million from residents.
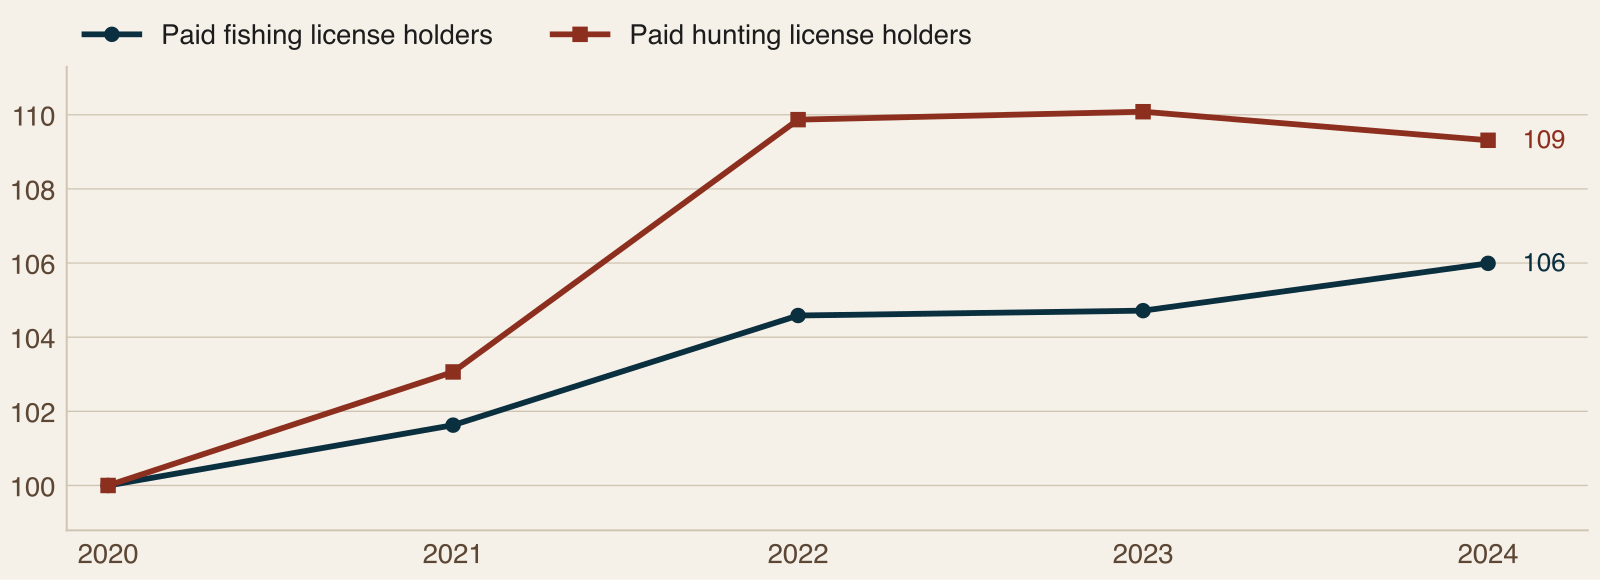
That revenue split is a reason for hunting operators to write for the traveler as well as the local. Federal surveys give a second window on bird hunters, with about 29,800 active duck hunters in 2024-25 and about 46,700 active dove hunters in 2025-26. The 2022 National Survey counts about 599,000 hunters and 1,700,000 anglers aged 16 and older, a different population from the license counts, so the report keeps them apart.
The 2026-27 Calendar and Coastal Limits
Deer archery opens Saturday, September 12, 2026 and firearms on Saturday, October 17, 2026. For most hunters the season ends January 10, 2027, though counties with extended seasons have other end dates. The bag limit is up to 10 antlerless deer and no more than 2 antlered deer, and every deer must be reported through Georgia Game Check within 24 hours. WRD estimated a harvest of 274,134 deer in 2024-25, with 52% antlerless, against a high of 298,022 in 2023-24. Quail runs November 14 to February 28 at 12 a day, or 3 per person on WMAs, VPAs and national forest land. Spring turkey 2027 runs March 27 to May 15 on private land and April 3 to May 15 on WMAs, VPAs and national forest land.
The wildlife trends matter to anyone selling a hunt. Reported spring turkey harvest was 11,570 in 2024 against 14,412 in 2020, down 20%, and WRD's summer poult survey shows 1.80 poults per hen in 2024, 1.58 in 2025 and a preliminary 1.47 in 2026. On quail, the National Bobwhite and Grassland Initiative's 2023 report lists an estimated harvest of 373,193 birds and 12,203 quail hunters in 2022, against 504,683 birds and 15,060 hunters in 2015, with a statewide population index down by more than 75% since 1966. The 2022 estimate includes pen-reared birds, so the report says the two harvest figures are not a like-for-like trend.
On the coast, Georgia's Coastal Resources Division publishes one set of limits for the whole coast rather than regional rules. Red drum are open all year at 5 fish with a 14 to 23 inch slot, spotted seatrout 15 fish with a 14 inch minimum, flounder 15 fish with a 12 inch minimum and sheepshead 15 fish with a 10 inch minimum. The Division has announced that from January 1, 2027 the red drum limit drops to three fish with a 15 to 24 inch slot, which is exactly the kind of change a guide's site should link to the current page for and not copy.
One Short Coast and a Large Freshwater Public
NOAA's recalibrated estimates count 3.8 million marine angler trips in Georgia in 2025, down 2% from 3.9 million in 2021 and 4% of all trips in the seven Southeast coastal states. Shore fishing was 66% of trips and private and rental boats 33%. Charter boats carried 24,868 trips, 0.6% of the state's total, and charter trips fell 24% from 32,925 in 2021, with a low of 22,589 in 2024. The report does not carry a standard error for mode-level estimates, so it asks readers to read the direction and not the exact numbers. The money per trip explains why the fleet still matters: NOAA's 2022 spending study puts a charter or guided angler-day at $270.56 against $69.30 for a shore angler-day, 3.9 times as much, and trip spending produced a $356 million sales impact in 2023, supporting about 2,281 jobs.
Most Georgia anglers fish fresh water. The 2022 National Survey counts about 1.6 million freshwater anglers against about 561 thousand saltwater anglers, and the three Corps of Engineers projects tagged to Georgia had 17.7 million visits in fiscal 2024, led by Lake Lanier at 11,418,528 visits, 1,004,933 of them for fishing, followed by Allatoona Lake at 5,894,190. To work as a saltwater guide, Georgia requires a saltwater fishing guide license, and the U.S. Coast Guard separately requires a captain's license to carry passengers for hire. The report did not verify a state license rule for freshwater guides, so check with DNR before selling a freshwater trip.
Public Land and the Rules for Guides
Much of the water and woods a Georgia guide sells is public, and the estate is layered. WRD manages 133 wildlife management areas on 1,149,664 acres, of which 498,622 acres are state-owned and most of the rest is under long-term or short-term lease, and some of it is national forest or other federal land, so more than one set of rules can apply on the same ground. The state's general WMA rule lists permitted uses and does not address guiding, and the report found no WRD page authorizing it, so confirm with WRD and the landowner first.
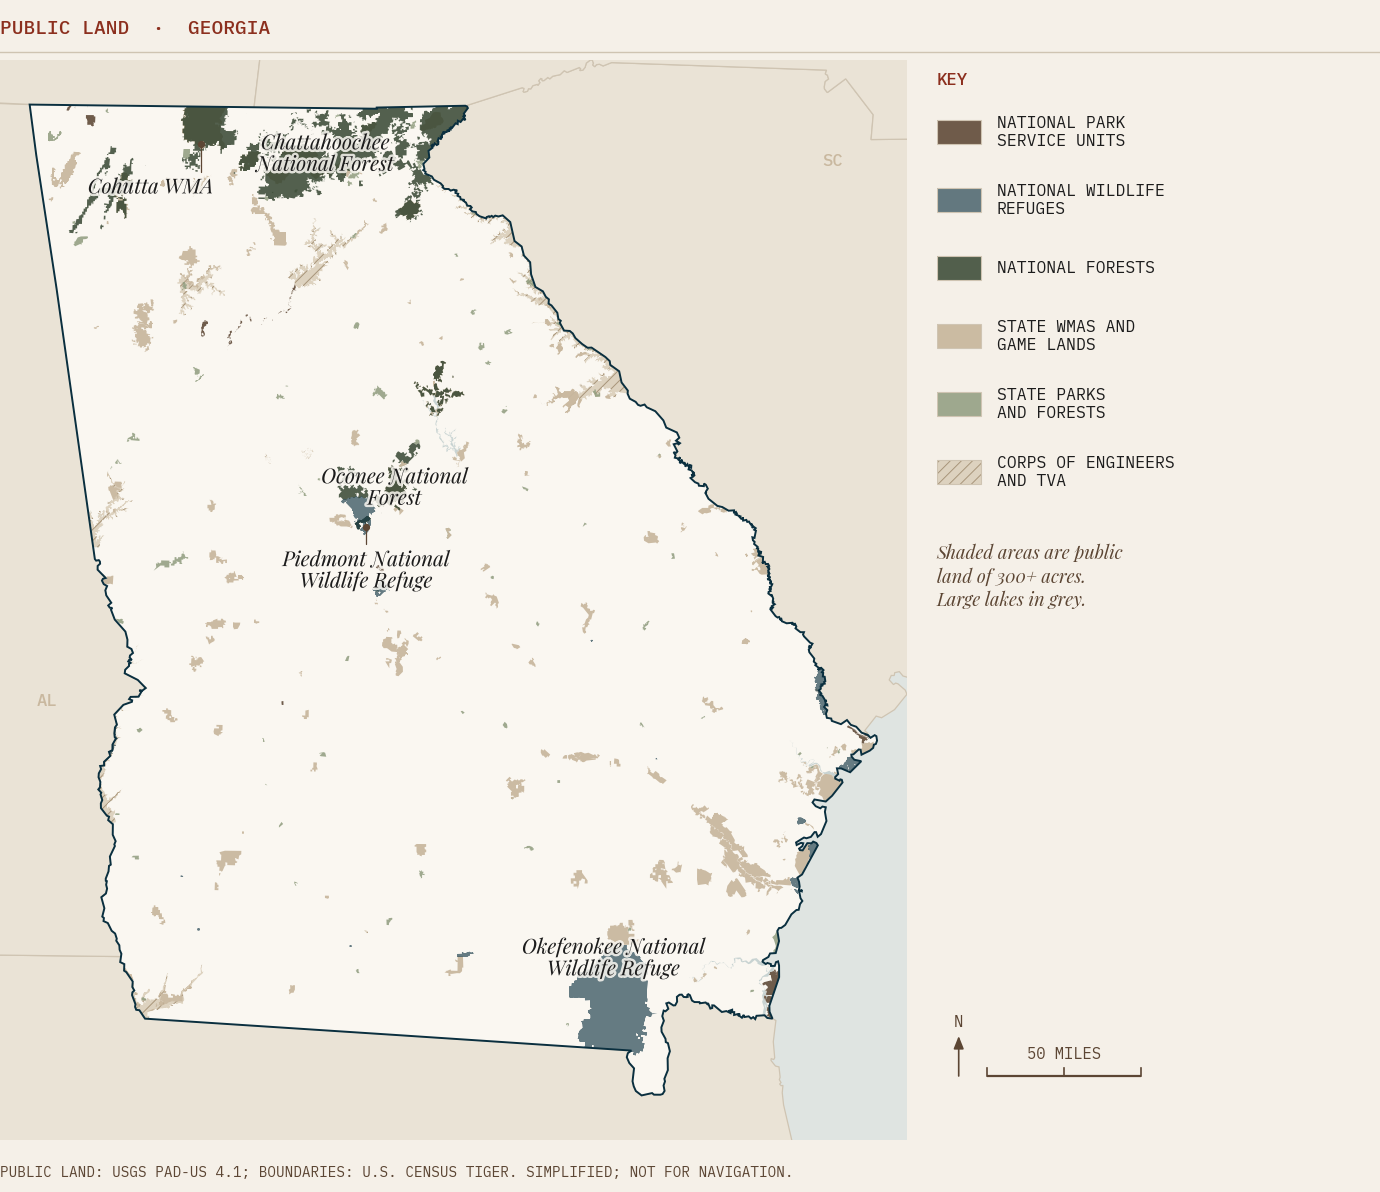
The Chattahoochee-Oconee National Forests require a special use permit for any outfitting or guiding business, and the forest takes applications in open seasons, August 1 to 31 and February 1 to 28 or 29. The Okefenokee National Wildlife Refuge, about 407,000 acres, requires a Commercial Guide special use permit for anyone who charges or includes a fee for guiding there, and its 2024 conditions describe annual permits, proof of liability insurance and first aid and CPR certification. Business operations in an NPS unit such as Cumberland Island National Seashore require a permit, contract or written agreement. The report did not verify a commercial guiding rule for state parks or Corps project lands, so ask the managing agency before selling a trip there. A refuge permit does not cover a national forest, and a state saltwater guide license is not a right to run a business inside a refuge or park.
What the Audit Adds
The report's operator chapter backs up the sub-region story. 87% of the 136 audited Georgia operators have their own website against 80% region-wide, and 35% score 4 or below against 40%. Of the 109 sites read, 28% show an online booking engine against 27% regionally, and where an engine shows, FareHarbor is the most common (13 of the 30 sites), followed by Wix Bookings (10) and Xola (4). 35% carry FAQ content, but only two of the 109 mark answers up as FAQ structured data, and 36% offer a newsletter signup against 33% regionally. 29% of sites with a detectable copyright year show 2023 or earlier.
The report shows all five larger sub-regions with figures. The Piedmont and central Georgia averages 5.69 across 26 operators, with 35% of sites read showing online booking and only 17% carrying FAQ content. The North Georgia mountains average 5.88, with 40% carrying FAQ content, and the Savannah coast 5.04, with only 71% of operators having their own website. The Golden Isles coast averages 5.50, with 50% carrying FAQ content, and the Southwest Georgia plantation belt averages 4.58 across 24 operators, 21 of them upland, plantation or sporting clays, with 17% of sites read showing online booking. The report notes that differences under half a point are noise and that Georgia's lead over the region is within the margin of noise.
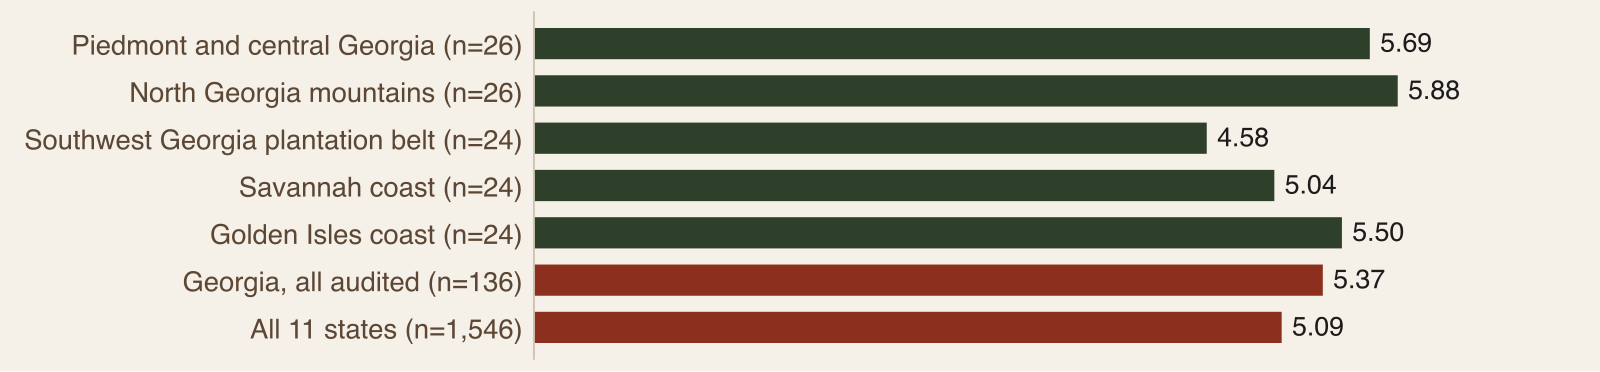
By category, upland, plantation and sporting clays is the largest at 33 operators and averages 4.82 against 5.21 across the 82 such operators in the eleven states. Fly fishing and trout averages 6.06 across 17 operators against 5.53 across 126, inshore and flats fishing 5.11 across 18 against 4.69, and paddle, kayak and canoe 5.45 against 5.36. The report's tier check shows Georgia close to the region: top-tier operators average 7.39 against 7.06, middle-tier 5.17 against 4.95 and lower-tier 3.08 against 2.84. The separate hunting audit counts 69 Georgia hunting operators with a mean of 5.62, and only 15% of the 62 sites read show online booking against 28% of the state's main-audit sites.
Read the full 2026-27 Georgia Outdoors report
Pine & Marsh's 2026-27 Georgia Outdoors report sets public data on the state's outdoor economy, hunters, anglers and public land beside our operator audit. Headline findings:
$20.7 billion of value added in 2024, 2.3% of GDP, ranked seventh of the eleven states.
815,738 paid hunting license holders in 2024, the highest count in the region.
A map of the state's major public land by managing agency. The state WMA rule does not address guiding and the report found no WRD page authorizing it, so confirm with WRD first. National forests need a Forest Service permit, and the Okefenokee refuge requires a commercial guide permit.
Download the full 2026-27 Georgia Outdoors report (free with your email).
Frequently Asked Questions
What makes marketing a sporting operation in Georgia distinctive?
Georgia is a state of contrasts, with Blue Ridge trout country, the Piedmont, the plantation belt and the barrier coast, so operators market across regions with different species and audiences, audited zone by zone. It is also the region's biggest hunting market, with 815,738 paid hunting license holders in 2024, and a big freshwater fishing public, so a Georgia operator usually sells into very different buyers depending on the sub-region.
What is the aggregator problem in Georgia?
Aggregators intercept discovery across the state's fisheries and hunts, so operators must build direct content and a funnel to recapture bookings and relationships. The audit shows the opening: only 28% of Georgia sites read show an online booking engine, and where one shows, it is often a third-party platform such as FareHarbor, on 13 of the 30 sites with one. A page that answers specific questions about your own water or property is something a listing page cannot offer.
How does AI search change the conversion funnel for Georgia operators?
AI answer engines increasingly sit at the top of the funnel, so operators must publish structured, citable content to be recommended rather than an aggregator. The audit did not measure which operators AI systems cite, but it did measure the groundwork: 35% of Georgia sites read carry FAQ content, and only two of the 109 mark answers up as FAQ structured data. Writing plain answers and marking them up is the clearest first step.
What are the strongest opportunities for Georgia operators?
The sub-regions with lower audit scores, such as the Southwest Georgia plantation belt at 4.58, and topics few operators have covered in depth are whitespace, so operators who publish authoritative regional and species content can stand out in searches competitors have left open. The report adds that Georgia's lead over the regional mean is within the margin of noise, and that hunting operators have the largest gap, with only 15% of audited hunting sites showing online booking.
How should Georgia operators position for AI engines?
By publishing structured, authoritative content engines can cite, since citability comes from structured content and signals, not a site alone. Cover specific species, places and seasons by name, answer the questions planning clients actually ask, and keep rule pages current and dated, because limits and seasons change. The audit counts 35% FAQ content and 2% FAQPage schema, so an operator who marks up honest answers is ahead of most of the sample.
What should a Georgia operator publish first?
Region- and species-specific content for their zone, conservation context, and structured data, so the operation is the source search and AI engines cite. The report's moves start with writing for the out-of-state visitor and hunter, making booking work on a phone, answering questions in structured form and publishing the permits you hold, such as a saltwater guide license, a Coast Guard captain's license, a Forest Service outfitter permit or a refuge commercial guide permit.
Can I guide on Georgia WMAs, national forests and the Okefenokee?
Each manager has its own rule. The state's general WMA rule does not address guiding, and the report found no WRD page authorizing it, so confirm with WRD and the landowner first. The Chattahoochee-Oconee National Forests require a special use permit for outfitting and guiding, with application windows in August and February, and the Okefenokee requires a Commercial Guide special use permit with liability insurance and first aid and CPR certification. Confirm with each agency before promoting trips.
What do Georgia's hunting license numbers say about the market?
Georgia has more paid hunting license holders than any other state in the region, 815,738 in 2024, up 9.3% from 2020, which is 7.3 per 100 residents. Nonresidents bought only 12% of hunting items but paid 53% of hunting license revenue, so out-of-state hunters carry more than half of what hunters spend on licenses. Items are not people, since one person can buy several, but the pattern argues for pages that answer a traveler's questions about license, access and what a day includes.
Work with Pine & Marsh
Pine & Marsh is a small, owner-operated marketing agency that specializes in sporting operations - guides, lodges, plantations, outfitters, and the conservation organizations and land trusts that partner with them. We built our framework on a verified 2026-27 audit of 1,546 private operators across 11 Southeastern states, and we apply it to individual engagements with the specificity and attention that a family-owned sporting business deserves.
If your Georgia operation matches the patterns we have described - a guide business that wants more of its bookings to come direct instead of through platforms, a plantation operation whose referral pipeline is aging, a coastal charter whose digital presence hasn't kept pace with the market - we want to talk. We start every engagement with a diagnostic of your current digital position. The first conversation is free.
Contact us through the intake form at pineandmarsh.com or reach Thomas Garner directly at info@pineandmarsh.com. We take on a small number of new Georgia clients each year.
Pine & Marsh is a southeastern outdoor marketing agency. Jacob Mishalanie and Thomas Garner founded the agency after working in and around sporting operations across the region. Contact us at pineandmarsh.com.


Comments