
The State of Outdoor Marketing in the Southeast: 2026-27 Data From 1,546 Verified Outfitter Audits
Updated: Oct 21

The Southeast Outdoor Economy Runs on a Thin Digital Layer
The eleven Southeast states from Virginia to Arkansas produced $176.7 billion in outdoor recreation value added in 2024, about a quarter of the U.S. total, according to the Bureau of Economic Analysis. They hold 29.9% of the country's paid hunting license holders and 29.8% of its paid fishing license holders while holding 25.7% of its population, per the U.S. Fish and Wildlife Service and the Census Bureau.
The businesses that guide, house and outfit that activity are a different story. In 2026 Pine & Marsh audited 1,546 private, for-profit outdoor operators across those 11 states and 97 sub-regions, from Shenandoah Valley trout guides to Toledo Bend bass guides and Florida Keys flats captains. Every business in the dataset was confirmed as real and currently operating, and every operator website was read by the same script on the same day.
The short version: the average operator scores 5.09 out of 10 on digital health, about two in five score 4 or below, and the tools that turn a search into a booking or a past client into a repeat client are missing from most operator websites.
This is the 2026-27 edition of the audit. It replaces the figures we published earlier this year, which drew on a larger but less rigorously verified list. The section on what changed explains why the numbers moved.
How the Audit Works
Each sub-region was built as a structured sample across three tiers: the most visible businesses in the market, the established middle, and the smaller or less visible operations. After verification removed duplicates, public entities and closed businesses, sub-regions average about 16 operators, and some come in well under that where we could not verify more real businesses. A smaller true sample beats a padded one.
Scope
1,546 private, for-profit outdoor operators confirmed as real and currently operating
11 states: Alabama, Arkansas, Florida, Georgia, Kentucky, Louisiana, Mississippi, North Carolina, South Carolina, Tennessee and Virginia
97 sub-regions defined by watershed, terrain and destination
About 20 business types, including fishing guides and charters, hunting outfitters and plantations, paddle and rafting outfitters, eco tours, marinas, lodges and campgrounds, and outfitter retail
Tourism boards, directories and editorial sites were identified separately and left out of every benchmark
What We Measured
Two layers, kept separate on purpose.
A digital health score from 1 to 10, assigned by a researcher from observed evidence: whether the business has its own website, how complete and current it is, how clearly it explains its services, seasons and booking, and how active its public listings are
Website signals read automatically from each operator's homepage on October 17, 2026: structured data (schema) types including FAQPage, FAQ content, newsletter or email signup, online booking engine, HTTPS, mobile viewport and the latest copyright year
Of the 1,546 operators, 80.2% have their own website, and 1,093 of those sites returned a readable page. Sites that blocked automated requests or timed out are excluded from the website-signal rates rather than guessed. Because the scan reads homepages only, website-signal rates are lower bounds: an operator may have an FAQ or a signup form deeper in the site.
The Headline Numbers
Mean digital health: 5.09 out of 10
Scoring 4 or below: 39.8%
Scoring 8 or above: 12.3%
Own website: 80.2%
Any FAQ content on the homepage: 36.9%
FAQPage schema: 2.0%
Newsletter or email signup: 32.7%
Online booking engine: 27.0%
Latest copyright year 2023 or older: 25.0%
HTTPS: 97.0%, and mobile viewport tag: 92.2%
The last line matters. The basic hygiene problems of a decade ago are mostly solved. Nearly every operator site loads securely and is built to display on a phone. The gap now is not whether a site exists but whether it does the work: answering the questions a buyer asks, capturing the people who visit, and letting them book.
State by State
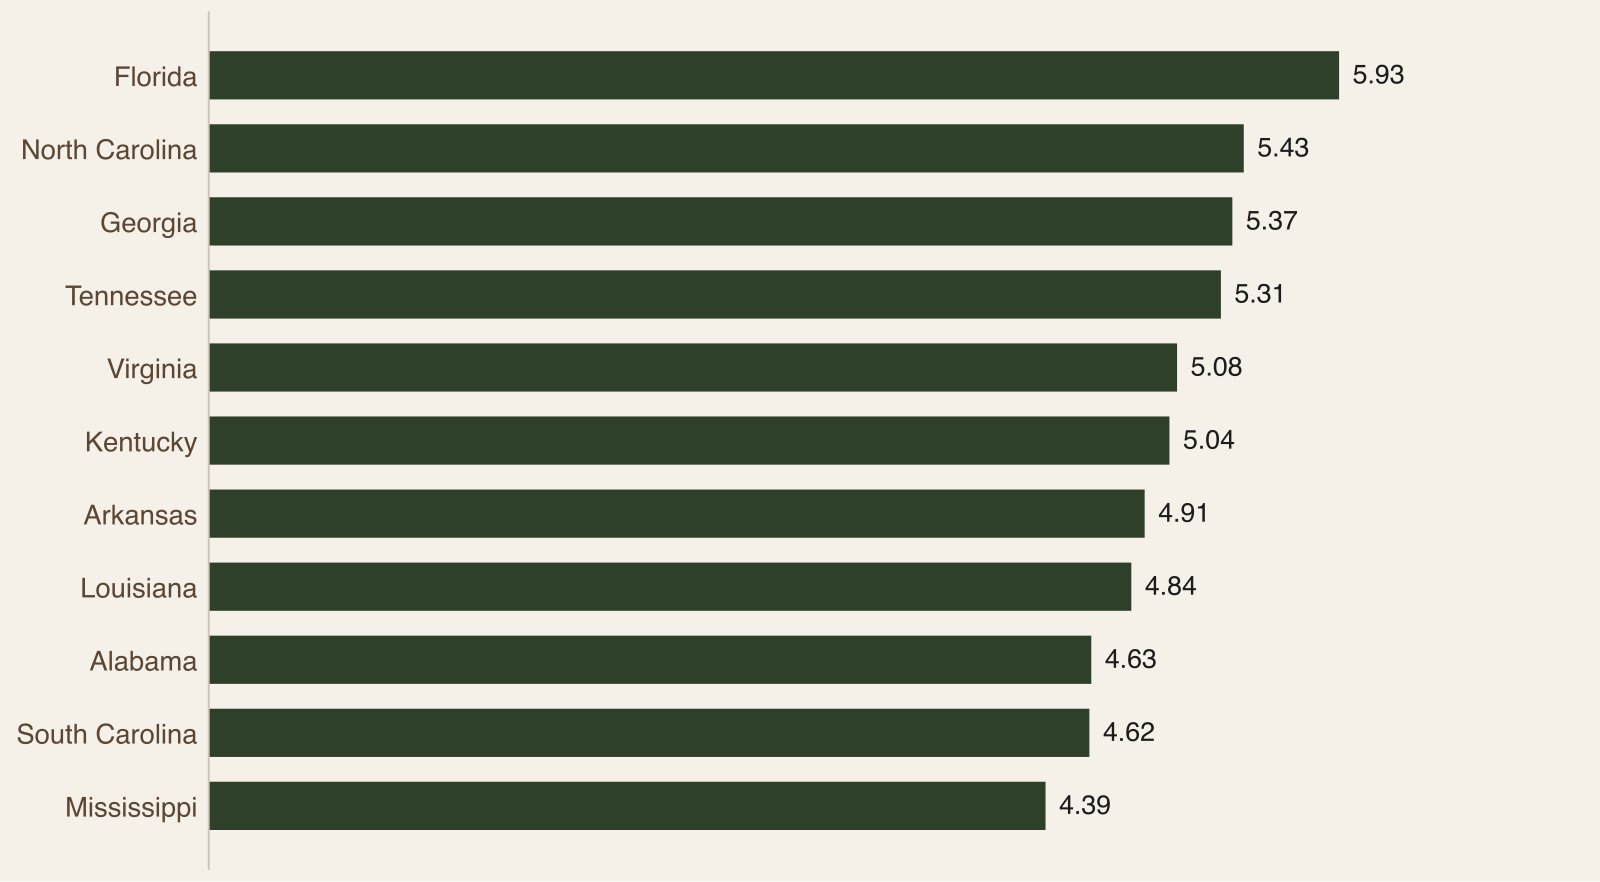
Mean digital health by state, from highest to lowest, with the number of audited operators:
Florida: 5.93 (117 operators)
North Carolina: 5.43 (243)
Georgia: 5.37 (136)
Tennessee: 5.31 (160)
Virginia: 5.08 (146)
Kentucky: 5.04 (102)
Arkansas: 4.91 (139)
Louisiana: 4.84 (146)
Alabama: 4.63 (138)
South Carolina: 4.62 (133)
Mississippi: 4.39 (88)
State samples run from 88 to 243 operators, so a difference of a few tenths of a point is within the noise. Counting only private businesses, Kentucky sits mid-pack, just below the region mean. The clearer story is the spread inside each state.
Florida leads on almost every measure. Its audited operators are the most likely to have their own website (94%) and by far the most likely to take bookings online (46%, against 27% region-wide). Busy charter and eco-tour markets in the Keys and Southwest Florida may be part of the reason, since booking engines suit scheduled trips sold to visitors.
Florida, Tennessee and North Carolina lead on content. Between 41% and 47% of their audited operator homepages carry FAQ content, and Tennessee has the highest newsletter signup rate in the region at 41%.
Mississippi, South Carolina and Alabama sit at the bottom. Mississippi has the lowest share of operators with their own website (61%) and the lowest rate of online booking (10%). South Carolina has the highest share scoring 4 or below (55%).
Sub-Regions Matter More Than States
Among the 43 sub-regions with at least 15 audited operators and at least 10 readable sites, the highest-scoring averages 7.29 and the lowest averages 3.67. Ten of the 43 average below 5.
The top of the list is dominated by destination markets with heavy visitor traffic: the Shenandoah Valley and Blue Ridge in Virginia, the Florida Keys, Southwest Florida, the Red River Gorge in Kentucky and the Outer Banks in North Carolina. The bottom is dominated by reservoir and marsh fishing markets, including northeast Alabama around Weiss Lake, the Chesapeake Bay shore of Virginia, the Alabama Black Belt, Greers Ferry Lake in Arkansas and Lake Ouachita. Small groups of audited operators around Toledo Bend, the Houma and Cocodrie marsh, central Mississippi and Santee-Cooper also scored low.
That split points to an opportunity rather than a verdict. Toledo Bend and Santee-Cooper are nationally known fisheries. The digital competition there is light, which means a single operator who builds a strong site in one of those markets has unusually little to beat.
Industry by Industry
The gap is widest between business types. Mean digital health for the larger categories in the dataset:
Whitewater rafting: 6.55 (38 operators)
Eco tours and wildlife viewing: 6.00 (101)
Fly fishing and trout: 5.53 (126)
Lodging and campgrounds: 5.40 (85)
Paddle, kayak and canoe outfitters: 5.36 (231)
Upland, plantation and sporting clays: 5.21 (82)
Offshore charter fishing: 5.15 (67)
Waterfowl hunting: 4.94 (34)
Marinas and boat rentals: 4.78 (132)
Inshore and flats fishing: 4.69 (196)
Bass, crappie and lake fishing guides: 3.83 (94)
Rafting outfitters and eco-tour operators, which sell scheduled trips to a broad visitor market, have built the most complete websites: 77% of rafting homepages carry FAQ content, and roughly half of rafting and eco-tour operators take bookings online. At the other end, only 4% of the bass, crappie and lake guide sites we could read take bookings online, and only 18% offer a newsletter.
A guide with a full calendar of regulars may not feel that gap today. It shows up when a new customer searches for a guide on that water for the first time.
Finding 1: FAQ Content Is a Wide-Open Lane
About 37% of operator homepages carry any FAQ content, and only 2.0% use FAQPage schema, the structured data that labels questions and answers for search engines and AI systems.
That second figure is the cleanest signal in the dataset of deliberate answer-engine work. Website builders such as Wix, Squarespace and many WordPress themes add basic Organization or LocalBusiness schema automatically, which is why 66.9% of operator homepages carry some schema and 53.4% carry a business type. Almost nobody has gone further and marked up the questions their buyers actually ask.
Those questions are predictable. When is the best month for redfish in the marsh? What should I bring on a first quail hunt? Do I need a fishing license on a guided charter in this state? Is the river runnable for kids in August? An operator who answers them plainly, on their own site, gives search engines and AI answer engines something specific and quotable to work with. Right now, in most sub-regions, those answers come from directories, forums, agency pages and travel media instead.
Finding 2: Two in Three Operators Have No Way to Stay in Touch
Only 32.7% of operator homepages offer a newsletter or email signup. The rest have no visible way to capture a visitor who is not ready to book today, or to bring a past client back next season.
For a business built on repeat clients, that is the quiet risk in the dataset. A referral network lives in an owner's phone and memory. An email list is an asset the business owns, one that survives a slow season, a change of booking platform or a change of ownership. Outfitter retail shops (59%) and whitewater outfitters (57%) are the most likely to collect emails. Lake fishing guides (18%) and horseback and trail-riding operators (14%) are the least.
Finding 3: Fewer Than One in Three Take Bookings Online
27.0% of operator homepages connect to an online booking engine. Platforms such as FareHarbor, Wix Bookings, Peek, Xola and Checkfront turn up among them.
Online booking is not right for every operation. Many plantation hunts, multi-day lodge stays and custom charters are better sold by conversation. But the range across the region is striking: 46% of Florida operators take bookings online, against 10% in Mississippi, 16% in Arkansas and 16% in Kentucky. For trips that are sold by the seat or the boat at fixed times, a visitor who cannot check dates at 10 p.m. often books with someone who lets them.
Finding 4: One Site in Four Looks Unattended
On 25.0% of operator homepages, the latest copyright year is 2023 or older. A copyright date is not proof that a site has gone untouched, but it is the first thing a careful buyer notices, and it often travels with outdated rates, seasons and photos.
Alabama (33%), Kentucky (30%) and Georgia (29%) have the highest shares of stale dates. South Carolina has the lowest share (9%).
Finding 5: The Leaders Show What Is Possible
The sample was built in three tiers per sub-region: the most visible operators in each market, the established middle, and the smaller or less visible operations. The most visible tier averages 7.06, the middle 4.95 and the smaller operations 2.84. Because tiers were assigned partly on visibility, that gap is expected, but it shows how far apart the two ends of each market are.
What the highest-scoring operators share is infrastructure: their own website with clear service, season and pricing information, content that answers first-timer questions, a way to book or inquire online, a way to stay in touch, and current public listings. None of that requires a large budget. It requires deciding to do it and keeping it current.
Where the Demand Is Moving: Licenses, Charters and Visitors
The audit shows how operators present themselves. Public data shows who is looking. Paid license counts from the U.S. Fish and Wildlife Service are the cleanest yearly read on the hunters and anglers a Southeast business can reach, and the trend from license year 2020 to 2024 is not the same everywhere. In six of the 11 states (Arkansas, Florida, Louisiana, Mississippi, South Carolina and Tennessee), outdoor recreation is a larger share of the state economy than the U.S. average of 2.4%, so the stakes are highest where the audit scores are often lowest.
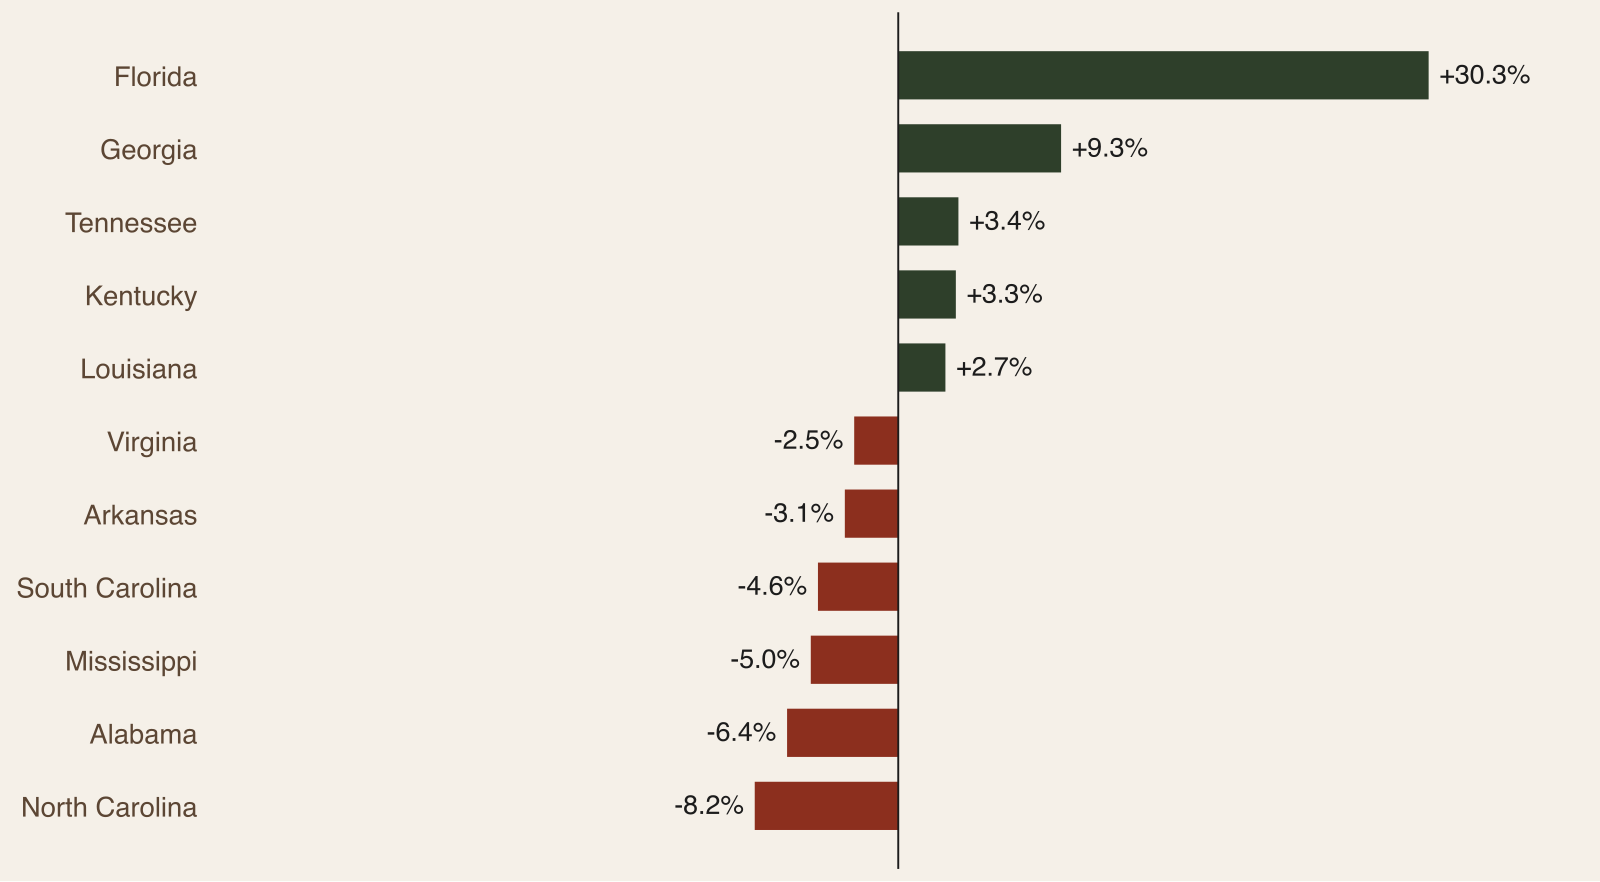
Hunting licenses grew in five states and shrank in six. Florida (up 30.3%) and Georgia (up 9.3%) gained the most hunting license holders, followed by Tennessee (up 3.4%), Kentucky (up 3.3%) and Louisiana (up 2.7%). North Carolina (down 8.2%), Alabama (down 6.4%), Mississippi (down 5.0%), South Carolina (down 4.6%), Arkansas (down 3.1%) and Virginia (down 2.5%) lost ground. Across the region the total was up 1.1%.
Fishing is a harder story. Regional fishing license holders peaked in 2021 and were 4.6% below that peak by 2024. Louisiana (down 13.8% since 2020), South Carolina (down 11.8%), North Carolina (down 9.1%) and Virginia (down 7.1%) saw the steepest falls, while Florida (up 8.3%) and Georgia (up 6.0%) grew. License holders are not unique people, since someone licensed in two states counts twice, and some swings, including Tennessee's 2022 hunting count and Florida's 2023 and 2024 hunting counts, likely reflect reporting changes. Read them as direction, not headcount.
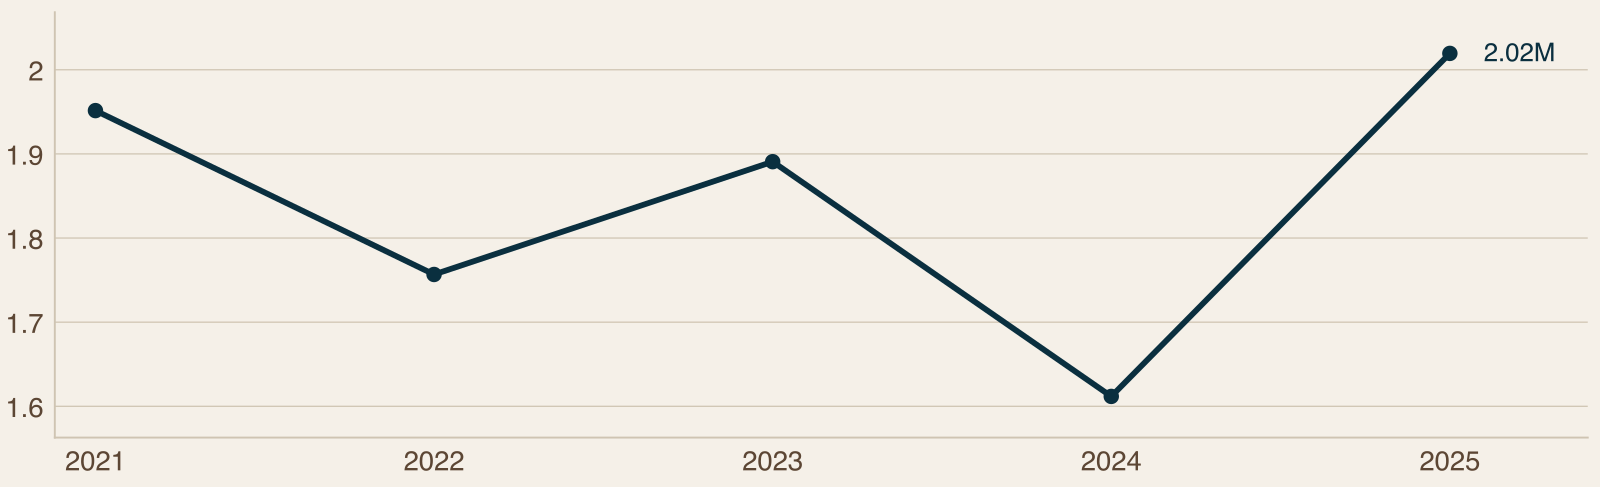
Saltwater runs the other way. Marine angler trips across the seven MRIP states rose from 100.0 million in 2021 to 108.7 million in 2025, and charter-boat angler trips reached 2.02 million in 2025, the highest of the last five years. Charter anglers also spend the most: NOAA's 2022 survey put for-hire spending per angler-day at $760 in Louisiana and $597 on Florida's Gulf coast, several times what shore anglers spend. NOAA recalibrated the series in August 2026, so these counts are lower than figures published before then and should not be compared with them.
Every first-time guest of a guide, lodge or rental arrives as a visitor first. State tourism offices report visitor spending from $10.2 billion to $46.2 billion per state in the latest year. Because the studies use different contractors and definitions, each figure is best read within its own state, and the report never adds visitor spending to BEA value added or to hunting and fishing spending, since they measure different things and overlap.
The resource side is mixed, and it affects what an operator can promise. The 2026 breeding survey counted 33.4 million ducks, about 6% below the long-term average, with mallards at 5.9 million, 26% below average. The 2026-27 frameworks for the Atlantic and Mississippi flyways still allow a 60-day season with a six-duck daily bag. On turkeys, spring 2026 brought record or near-record harvests in Kentucky (36,439), North Carolina (25,034, the highest since records began in 1977), Louisiana (4,024) and Arkansas (13,591), yet most states reported fewer than two poults per hen. Strong seasons and weak hatches can coexist, which is a reason to publish current, honest season information instead of last year's brochure copy.
Worked Examples: What an Operator Does With This
A hunting outfitter in Florida or Georgia is working in a growing license base. More licensed hunters means more first-time buyers, and first-time guests search with plain questions: when to come, what to bring, where to stay and what it costs to get licensed. A page that answers those questions and marks them up as FAQ is built for exactly that visitor.
An operator in North Carolina or Alabama faces the opposite trend, with hunting license holders down 8.2% and 6.4%. When the pool is shrinking, a past client is worth more than a new click. That is where an email signup and a clear rebooking path matter most, and it is the gap Finding 2 describes.
A charter captain sells scheduled trips to the customer who spends the most per day of any saltwater mode. Posting open dates and letting visitors book or inquire online fits that kind of trip, which is the same pattern the audit shows in the Florida booking numbers above.
A waterfowl guide should say plainly what the 2026-27 season looks like: a 60-day season, a six-duck daily bag that includes up to four mallards (two hens) and three pintails. A guide who explains that clearly gives hunters something to rely on in a year when breeding mallards sit 26% below their long-term average.
Rules content belongs in the same plan. Commercial guiding on wildlife management areas, national wildlife refuges and national forests is restricted or permit-based in much of the region, so a page about a public-land trip should name the managing agency and tell readers to confirm its current rules. An operator who guides on public land needs the right state or federal permit before advertising the trip.
What Changed From Our Earlier Figures
Our earlier 2026 figures described a much larger list of operators and a mean digital health score of 5.56. In October we re-verified every record in that dataset, one by one, against live websites, listings and public records. A substantial share could not be confirmed as real, currently operating businesses, so we rebuilt every sub-region to a stricter standard and kept only businesses with observed evidence. A final classification pass then removed state parks, public agencies, nonprofits and businesses whose main product is not outdoor recreation, so the audit now covers private, for-profit operators only.
The verified dataset is smaller and the picture is less flattering. The mean fell from 5.56 to 5.09, and the share of operators scoring 4 or below rose from about 27% to 39.8%. We also replaced several judgment-based measures with signals read directly from each website by a single script, so the 2026-27 figures are measured the same way in every state. Older figures on schema, FAQ pages and newsletters are not directly comparable and should not be cited alongside these.
What the Data Means for Operators
The Southeast outdoor economy is large and heavily dependent on visitors who research before they book. The digital layer that connects those visitors to operators is thin almost everywhere and close to empty in many fishing and hunting markets.
The practical steps follow directly from the data:
Answer the questions buyers ask, on your own site: seasons, species, what to bring, licensing, group sizes, lodging and cancellation terms
Mark those answers up with FAQPage schema so search and AI engines can read them as answers
Add a simple email signup and use it at least a few times a year
Offer online booking or a clear online inquiry path for trips that suit it
Keep the site visibly current, starting with this season's dates, rates and photos
Whether you run a two-boat guide service on a reservoir or a multi-generation plantation, those steps cost far less than the trips they help book. In most of the sub-regions we audited, the operator who takes them first will have very little competition.
Pine & Marsh works with outdoor operators across the Southeast. If you want to see how your sub-region compares, reach out and we will share what the data shows about your market.
Sources
Pine & Marsh Southeast Outfitter Audit, 2026-27 edition: 1,546 verified private operators in 97 sub-regions, records verified in October 2026 and homepage signals read October 17, 2026
NOAA Fisheries, Marine Recreational Information Program, 2021 to 2025 estimates, recalibrated series released August 31, 2026
U.S. Fish and Wildlife Service, Waterfowl Population Status 2026, state tourism office visitor-spending reports (2024 and 2025), state wildlife agency turkey harvest and brood reports, and Southwick Associates studies for the American Sportfishing Association and the Sportsmen's Alliance Foundation (2022 data), as cited in the full report
What the full Southeast report adds
The 2026-27 Southeast Outdoor Economy report sets public data beside our audit and goes past the figures above, with state-level numbers, harvest trends and visitor spending.
Florida's $65.3B in outdoor recreation value added is more than three times Georgia's $20.7B, and 3.8% of Florida's GDP, the highest share in the region.
Regional hunting license holders were up 1.1% from 2020 to 2024, while fishing license holders were 4.6% below their 2021 peak.
In 2022, anglers spent $37.6B across the 11 states and hunters spent $15.1B.
Download the full 2026-27 Southeast Outdoor Economy report (free with your email).
Frequently Asked Questions
How many outfitters did Pine & Marsh audit, and how were they chosen?
The 2026-27 audit covers 1,546 private, for-profit outdoor operators across 11 Southeast states and 97 sub-regions, each confirmed as a real, currently operating business in October 2026. Each sub-region was built as a structured sample across three tiers: the most visible businesses, the established middle, and smaller or less visible operations. That averages about 16 operators per sub-region. State parks, public agencies, nonprofits, tourism boards and directories are left out of every benchmark.
What is the average digital health score, and which states lead?
The mean is 5.09 out of 10, and 39.8% of operators score 4 or below. Florida leads at 5.93, followed by North Carolina at 5.43, Georgia at 5.37 and Tennessee at 5.31. Mississippi is lowest at 4.39, with South Carolina at 4.62 and Alabama at 4.63. State samples run from 88 to 243 operators, so a gap of a few tenths of a point is within the noise. The spread inside each state is the clearer story.
Why does the 2.0% FAQPage schema figure matter?
FAQPage schema is the structured data that labels questions and answers so search engines and AI answer engines can read them cleanly. About 37% of operator homepages carry some FAQ content, but only 2.0% mark it up. Many website builders add basic business schema automatically, which is why 66.9% of homepages carry some schema, yet almost nobody has marked up the questions buyers actually ask. That leaves most sub-regions with answers coming from directories, forums and agency pages.
Do most outfitters run an email newsletter or take bookings online?
No. Only 32.7% of operator homepages offer a newsletter or email signup, and 27.0% connect to an online booking engine. Booking varies widely by state: 46% of Florida operators take bookings online, against 10% in Mississippi and 16% in both Arkansas and Kentucky. Online booking is not right for every operation, since plantation hunts, multi-day lodge stays and custom charters are often better sold by conversation, but trips sold by the seat or boat suit it well.
Why are these numbers different from earlier Pine & Marsh figures?
In October 2026 we re-verified every record against live websites, listings and public records. A substantial share could not be confirmed as real, currently operating businesses, so we rebuilt every sub-region and kept only confirmed private operators. The mean fell from 5.56 to 5.09, and the share scoring 4 or below rose from about 27% to 39.8%. We also replaced judgment-based measures with signals read by one script, so older schema, FAQ and newsletter figures should not be cited beside these.
Which states are gaining and losing hunters and anglers?
From license year 2020 to 2024, Florida (up 30.3%) and Georgia (up 9.3%) gained the most hunting license holders, while North Carolina (down 8.2%) and Alabama (down 6.4%) lost the most. Regional hunting license holders were up 1.1% overall. Fishing license holders peaked in 2021 and were 4.6% below that peak by 2024, with Louisiana down 13.8% and South Carolina down 11.8% since 2020. License holders are not unique people, so treat these as trends in licenses, not headcounts.
Is charter fishing demand growing in the Southeast?
The public data says yes. Charter-boat angler trips reached 2.02 million in 2025, the highest of the last five years, and marine angler trips across the seven MRIP states rose from 100.0 million in 2021 to 108.7 million in 2025. NOAA's 2022 survey put for-hire spending per angler-day at $760 in Louisiana and $597 on Florida's Gulf coast. NOAA recalibrated its series in August 2026, so compare these counts only with other recalibrated figures.
Can I guide on public land in the Southeast?
It depends on the land and the managing agency. Commercial guiding on wildlife management areas, national wildlife refuges and national forests is restricted or permit-based in much of the region, and the rules differ by state and by agency. National forests need a U.S. Forest Service special-use permit, and National Park Service units need a commercial use authorization or concession contract. Confirm with the managing agency before advertising any public-land trip.
Where should a small operator start?
Start with the five steps the data points to: answer the questions buyers ask on your own site, mark those answers up with FAQPage schema, add a simple email signup and use it a few times a year, offer online booking or a clear inquiry path for trips that suit it, and keep the site visibly current, beginning with this season's dates, rates and photos. In most sub-regions we audited, the operator who does this first faces very little competition.


Comments