
Inside the 2026-27 Waterfowl Report: Hunters, Breeding Numbers and the Duck Guide Storefront
Waterfowl in the Southeast, 2026-27 Edition, is Pine & Marsh's second industry report. It looks at duck and goose hunting demand, the state of the resource, and the digital storefronts of the Southeast's waterfowl guides and outfitters. It draws on the U.S. Fish and Wildlife Service Harvest Information Program and Waterfowl Population Status report, USFWS license data and the Bureau of Economic Analysis, plus a Pine & Marsh audit of hunting businesses in 11 states.
It is written for duck and goose guides, outfitters and lodges, and for anyone planning to sell hunts this fall. This post takes the report one chapter at a time, in the report's order. For the marketing playbook, see Marketing a Waterfowl Guide Service in the Southeast.
The Industry in Nine Numbers
The report opens with the scale of the sport. HIP counted 1.19M active duck hunters in the U.S. in 2025-26, 26% above the 2015-24 average of 942K, and the U.S. harvested 14.9M ducks and 3.65M geese. In 2024-25 the 11 states held 32% of active U.S. duck hunters and produced 38% of the national duck harvest. The U.S. Fish and Wildlife Service changed its survey methods in 2023, so the rise should not be read as a clean trend.
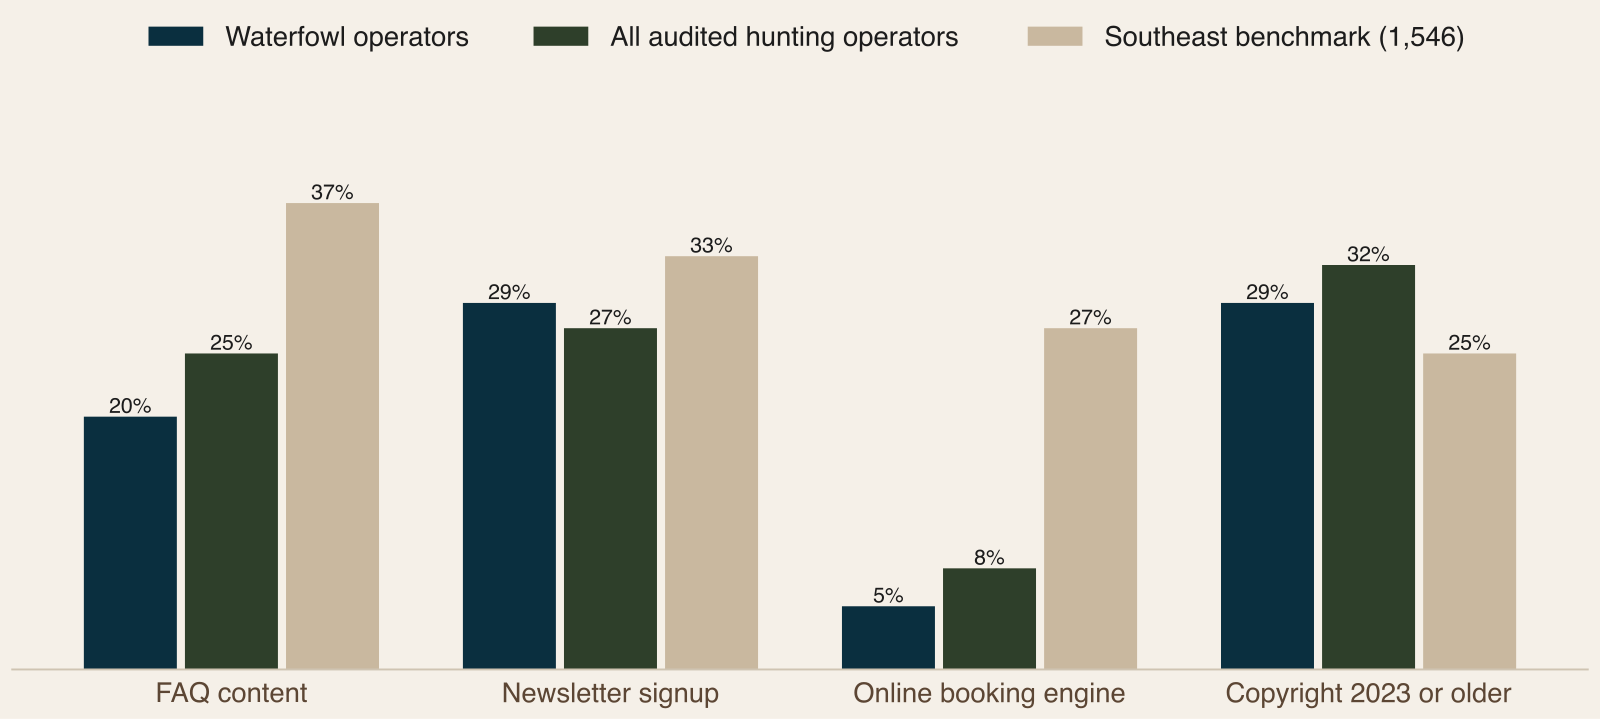
The soft spot is the resource: May 2026 breeding mallards were 5.9M, 26% below the long-term average. On the business side, the audit sample has 139 waterfowl operators, 28% of the 493 audited hunting operators. Their mean digital health is 5.32 out of 10, against 5.23 for all audited hunting operators and 5.09 for the Southeast benchmark. Only 5% show an online booking engine on the homepage, and 20% have FAQ content, against 36.9% in the benchmark.
Demand: Who Hunts Waterfowl
No public source counts everyone who hires a waterfowl guide. The closest measure is HIP, a survey of active duck and goose hunters and what they harvest, so every figure has a margin of error. Nationally, HIP counted 1,188,400 active duck hunters in 2025-26, up from 1,159,400 the season before. Goose hunters numbered 629,600.
For the 11 states, 2024-25 state estimates put 369,200 active duck hunters in the region, 32% of the national count, and 121,300 active goose hunters. Arkansas (75,100) and Louisiana (58,900) lead by a wide margin, with Tennessee and North Carolina next. Between the two most recent seasons, active waterfowl hunter counts moved little in most states. Mississippi is the exception, falling from 28,700 to 20,500, and Arkansas rose from 70,300 to 79,400. Goose hunter counts in Florida, Alabama and South Carolina carry very wide margins of error and should be read as small and uncertain.
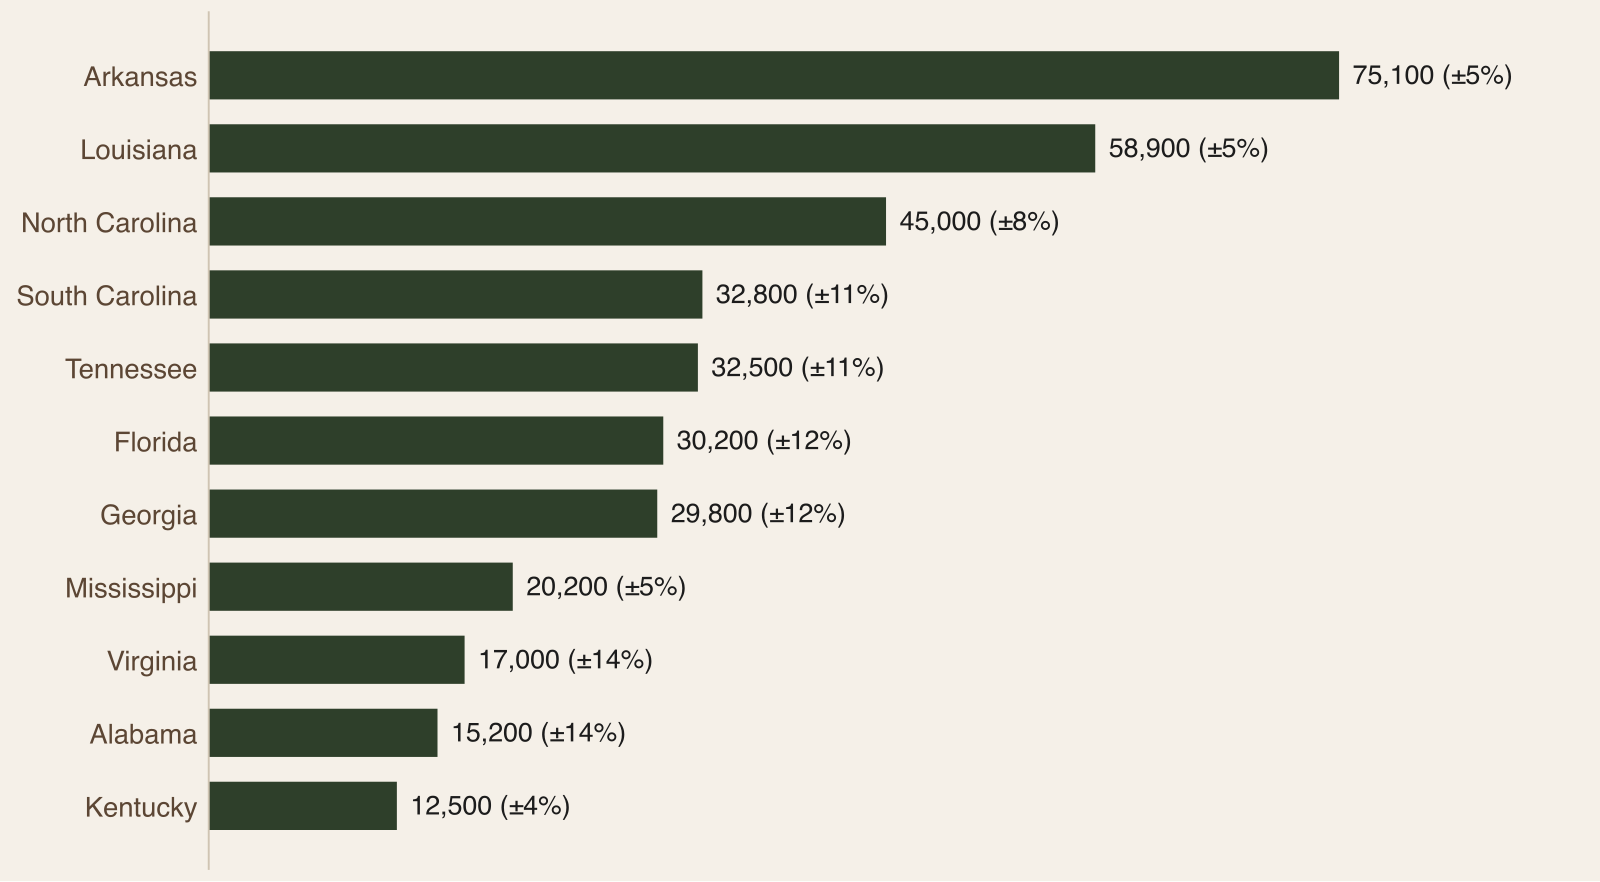
The rest of the state table fills in the middle of the pack. North Carolina had 45,000 active duck hunters, South Carolina 32,800, Tennessee 32,500, Florida 30,200 and Georgia 29,800, followed by Mississippi (20,200), Virginia (17,000), Alabama (15,200) and Kentucky (12,500). Compared with 2023-24, active waterfowl hunters rose 13% in Arkansas and in Florida, 7% in Louisiana, 6% in South Carolina and 5% in Alabama, and fell 29% in Mississippi, 8% in Virginia, 7% in North Carolina and 3% in Georgia. Nationally the 2025-26 numbers add context: duck harvest was 14,910,800 against a 2015-24 average of 11,255,900 (up 32%), goose hunters numbered 629,600 and goose harvest was 3,653,900.
The wider hunting market is large. The 11 states had 4,714,399 paid hunting license holders in 2024, 29.9% of the U.S. total. The 2022 National Survey counted 14.4 million hunters age 16 and older nationally, about 2.8 million of whom hunted migratory birds, which includes doves, so that is an upper bound for waterfowl. BEA value added from hunting, shooting and trapping reached $16.5 billion in 2024, up 95% from $8.5 billion in 2019.
The report is careful about what this means. HIP measures active hunters and birds retrieved, not what hunters pay guides, and much waterfowl hunting is done on public land, on leased or owned private water, or in clubs. These figures describe the pool a guide draws from, not the size of the guided market.
The Resource and the Season Framework
The May 2026 breeding survey estimated 33.4 million breeding ducks, 6% below the long-term average of 35.4 million. Mallards were 5.9 million, 11% below 2025 and 26% below their long-term average of 7.9 million. Northern pintails (2.0 million) were 48% below average. Blue-winged teal were 4.0 million and gadwall 2.4 million.
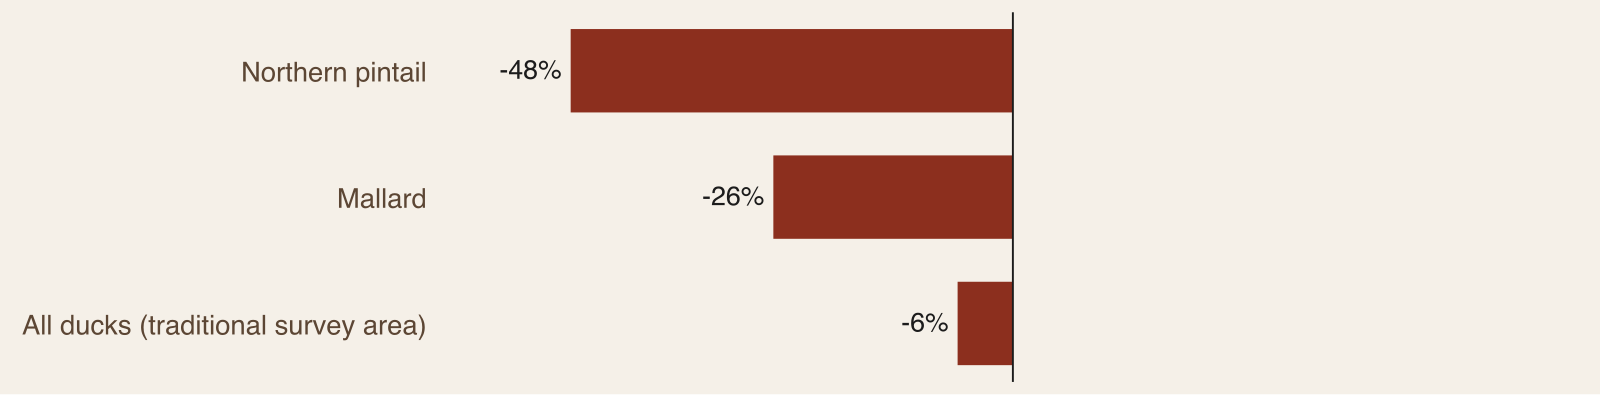
Breeding numbers are one input to fall flights. Habitat, weather in the north and conditions on the wintering grounds also shape how many birds reach the Southeast and when. The report's advice to operators who sell a season's worth of hunts is to describe conditions as they are and avoid promising numbers.
Harvest in the 11 states was 5,403,300 ducks in 2024-25, up 7% from 5,057,300 the season before, which is 38% of the U.S. harvest. Seven states rose and four fell, but most changes are smaller than the survey's margins of error. Only Arkansas and Mississippi cleared the combined margins by the report's simple screen, and Mississippi's drop from 382,600 to 274,400 is the clearest. For 2025-26, the Mississippi Flyway harvested 6,974,900 ducks and the Atlantic Flyway 2,333,300, together 62% of the U.S. duck harvest.
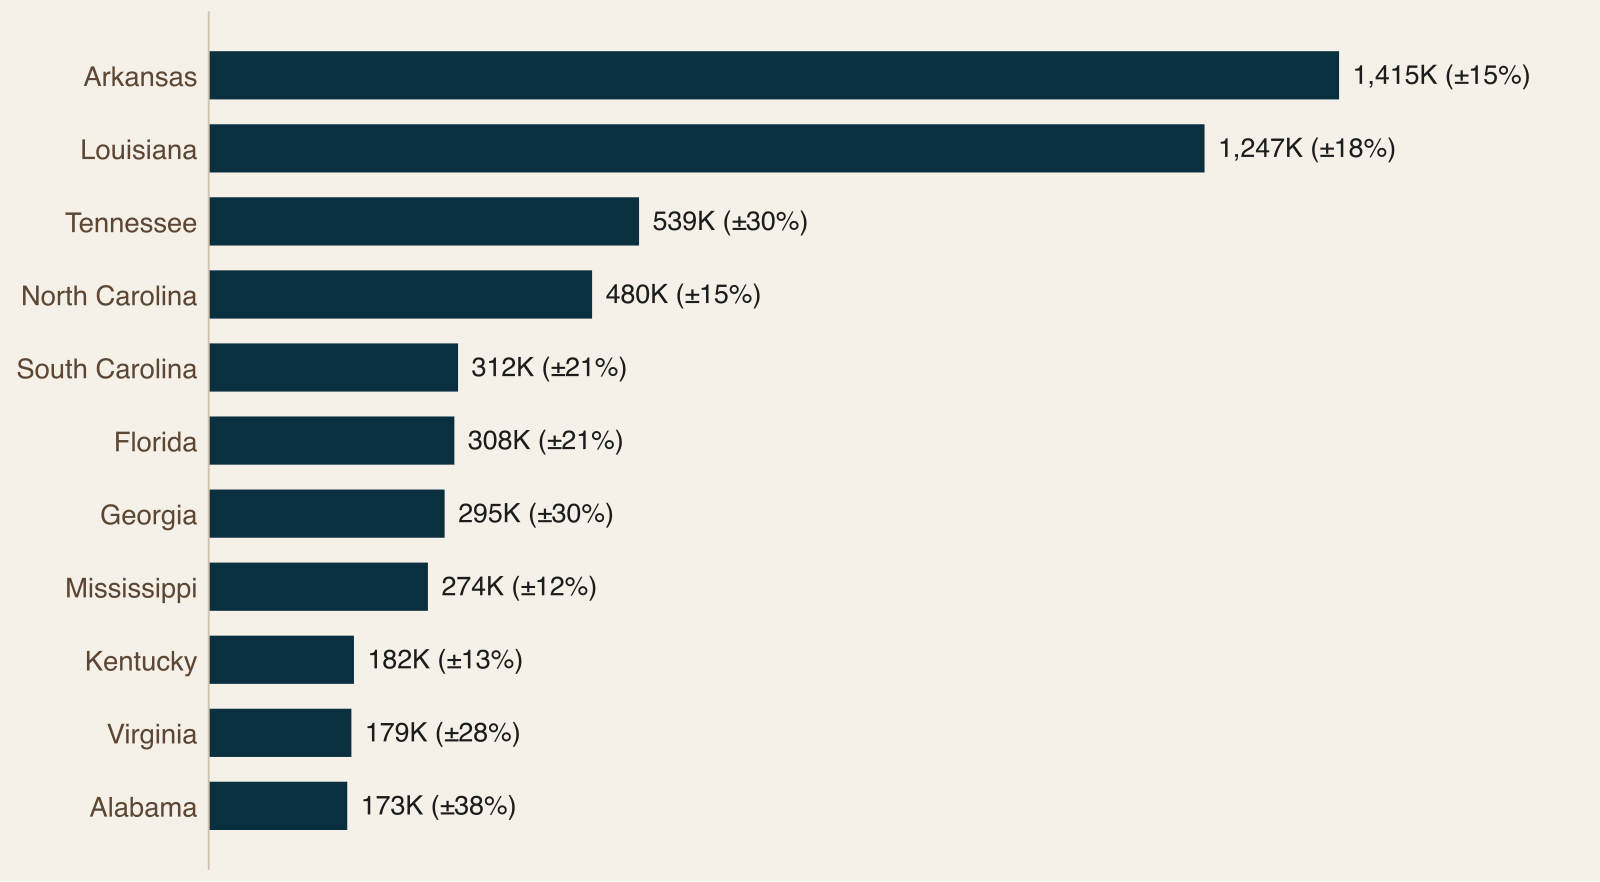
State by state, the 2024-25 duck harvest was 1,415,000 in Arkansas (up 25%), 1,246,600 in Louisiana (up 14%), 538,700 in Tennessee (down 10%), 479,900 in North Carolina (up 8%), 312,100 in South Carolina (up 5%), 307,500 in Florida (up 24%), 295,300 in Georgia (up 8%), 274,400 in Mississippi (down 28%), 181,800 in Kentucky (up 8%), 178,600 in Virginia (down 18%) and 173,400 in Alabama (down 14%). The margins of error run from 12% in Mississippi to 38% in Alabama, which is why the report marks only Arkansas and Mississippi as clear changes. Goose harvest across 10 states was 528,600, with Florida's figure not extracted from the source report. At flyway level for 2025-26, the Mississippi Flyway had 483,300 active duck hunters and the Atlantic Flyway 271,600, and the Mississippi Flyway's goose harvest was 1,715,600 (up 23%) against 556,100 in the Atlantic Flyway.
The 2026-27 federal framework is steady. The Atlantic and Mississippi Flyways have the same duck framework: a season of up to 60 days and a daily bag of 6 ducks, of which no more than 4 may be mallards (no more than two of them hens), 3 pintails and 3 wood ducks. Louisiana has a new experimental season for black-bellied whistling ducks of 9 days and 4 birds a day. USFWS has also moved to setting federal limits every three years, not every year. The report does not list state season dates, so post your own from the current state regulations.
Public land needs its own note. Much of the best-known waterfowl water in the Southeast is public: state wildlife management areas, national wildlife refuges and national forest land. Commercial guiding there generally requires a permit or special-use authorization from the managing agency, and some units do not allow it at all. Never advertise a hunt on public land without the permit for that unit, and confirm with the managing agency.
Where It Happens
The audit has 139 waterfowl operators across the 11 states. Louisiana (28) and Arkansas (27) hold 55 of them (40%), and the five largest states, Louisiana, Arkansas, Tennessee, Mississippi and North Carolina, hold 96 (69%). Arkansas and Louisiana also lead the HIP data for active duck hunters and duck harvest, so the audit and the public data point the same way at the top.
Waterfowl is largest as a share of a state's own audited hunting operators in Arkansas (73%) and Louisiana (64%) and smallest in Alabama (9%). The report adds three cautions. A small audit count does not mean a state has few hunts. Georgia and South Carolina show why: the research found waterfowl there mostly sold as preserve or membership-club hunting, which a sample built from verified listings captures differently from guided hunts. HIP counts hunters in a state, and many travel. And eight states have fewer than 15 audited waterfowl operators each (69 combined), too few to describe with percentages.
The state table in the report lines up the public numbers with the audit counts. After Louisiana (28) and Arkansas (27), Tennessee has 15 audited waterfowl operators, Mississippi 14, North Carolina 12, Florida 10, Kentucky 9, Georgia 8, Alabama 6, and South Carolina and Virginia 5 each. As a share of each state's audited hunting operators, waterfowl is 41% in Mississippi, 33% in Tennessee, 30% in Florida, 24% in Kentucky, 20% in Virginia, 19% in North Carolina and 12% in Georgia and South Carolina. The research behind the audit found guides concentrated in Arkansas, Louisiana, Mississippi, Tennessee and North Carolina, with North Carolina's around Mattamuskeet and Hyde County.
The Business Landscape
This chapter describes an audited sample: 493 hunting businesses, of which 139 (28%) carry a waterfowl tag. Every business was confirmed as operating before it was included. The sample is not a census, so it shows what verified operators look like, not every guide.
96% of waterfowl operators have their own website, and 130 of 139 sites returned a page and were read. Mean digital health is 5.32, with 32% scoring 4 or below, close to the 5.23 for all audited hunting operators (34% at 4 or below) and the 5.09 of the 1,546-operator Southeast benchmark (39.8% at 4 or below). Three of the other seven species tags score higher than waterfowl, and the spread is small.
Waterfowl is often sold with other hunts. Of the 139 operators, 65 carry no other species tag, so 74 (53%) sell something else as well. 48 are also tagged as lodges, 34 as whitetail and 29 as upland. A duck-hunting buyer can land on a homepage that is also selling deer, quail and lodging, and has to find the waterfowl page quickly.
Waterfowl also sits in the middle of the eight species tags. Mean digital health is 5.87 for sporting clays, 5.82 for lodges and 5.56 for wild hog, all above waterfowl's 5.32, with turkey (5.30), upland (5.29), whitetail and dove (5.11) below. Waterfowl's FAQ rate is 20% and its newsletter rate 29%. Its booking rate, 5%, is the lowest of the eight.
Only three states have enough operators to show separately. Louisiana has mean digital health of 5.39, Arkansas 5.56 and Tennessee 5.53, while the other eight states combined (69 operators) average 5.14 and show 9% with FAQ content against 31% in the three larger states. The report treats state differences smaller than about 10 percentage points, or half a point of score, as noise at these sample sizes.
How Buyers Search and Book
The audit shows what a visitor finds on a homepage, not how any one buyer searches, so the report's description of buyer behavior is general guidance. What the homepage scan does show:
5% of the 130 waterfowl sites show an online booking engine, the lowest booking share of the eight species tags, against 8% for all audited hunting operators and 27.0% in the benchmark.
20% of homepages carry FAQ content, against 36.9% in the benchmark and 25% across hunting. Only 1 of 130 uses FAQ structured data, although 60% have some structured data, much of it added automatically by website builders.
29% offer a newsletter signup, close to the benchmark's 32.7%.
29% of sites with a detectable copyright year show 2023 or earlier, against 25.0% in the benchmark.
For hunts sold by phone and deposit a low booking rate is not a surprise. It is still a gap, because a buyer who finds the site at ten at night has nothing to act on until morning. All rates are lower bounds, since a feature may sit deeper in a site.
The Season and Booking Calendar
The calendar is general guidance, not audit or public data. It runs in five phases: February to June, July and August, September and October, November to January, and end of season and after. The pattern is that waterfowl demand is concentrated in the fall and winter season, most of the selling is done before it starts, and the best-informed buyers book when state dates are announced.
Phase by phase, the report suggests the following. From February to June, close out the season: thank guests, collect reviews and photos with permission, ask who wants next year's dates and review the site for stale text and the copyright year. In July and August, publish next season's rates, party sizes and policies with a note that dates follow the state's season, and open a waiting list for past guests. In September and October, post season dates as soon as the state does, add availability and a deposit step, and update the FAQ for current licenses and stamps. From November to January, keep availability current, answer messages the same day, share honest hunt reports and ask every party for a review. After the season, offer returning guests first choice of next year's dates and send a thank-you with a rebooking link.
The report also sketches four kinds of buyer: the local day hunter, the out-of-state hunter, groups and corporate hosts, and returning guests and club members. Each books differently, and each needs something different from your site. Its advice is to build your own calendar from your last two seasons of bookings.
The detail is practical. A local day hunter decides close to the date when weather and birds line up, so last-minute availability, a text or call link that works on a phone and a clear weather policy matter. An out-of-state hunter plans weeks or months ahead around travel and lodging and asks about licenses and stamps, so publish dates, rates, a licensing and stamps checklist and lodging or lodging partners. Groups and corporate hosts book early and need a quote and a deposit, so give them a group page with capacity, minimums and a quick inquiry form. Returning guests and club members rebook when reminded, so keep an email list and a clear process for holding dates. This is general guidance, not measured behavior, so check your own booking records for actual lead times.
Six Moves for Operators
The report closes with six moves: publish next season's rates, dates and availability early; make it possible to book or hold a date online; answer buyers' questions and mark them up; say where and on what authority you hunt; give waterfowl its own page; and keep a list and use it. If you can do one thing this month, put the season's rates, dates and a way to hold a date on the homepage, and make it work on a phone.
What It Means for Operators
Demand is real and concentrated. Arkansas and Louisiana carry the harvest, and the 11 states account for 38% of the national duck harvest. The resource is the soft spot, with mallards and pintails well below their long-term averages, so sell the experience honestly and do not promise bird numbers.
The storefront gap is easy to see and cheap to close. Waterfowl has the lowest online booking share of the eight species tags, answers are thin, and 74 of 139 operators sell more than ducks and geese. A clear waterfowl page, a date-hold step, a short FAQ and a current footer put an operator ahead of most of the sample. On public water, hold the permit for the unit and say so.
Read the Full Waterfowl Report
The full report has every state table, the margins of error and the methodology.
Download the full 2026-27 Waterfowl report (free with your email).
Frequently Asked Questions
How many waterfowl hunters are there in the Southeast?
HIP counted 369,200 active duck hunters and 121,300 active goose hunters in the 11 states in 2024-25, 32% and 20% of the national counts. Arkansas (75,100) and Louisiana (58,900) lead by a wide margin. These are sums of state survey estimates with margins of error, and a hunter active in more than one state may be counted in each. No public source counts everyone who hires a waterfowl guide, so these figures describe the pool a guide draws from.
Which states harvest the most ducks?
Arkansas (1,415,000 ducks in 2024-25) and Louisiana (1,246,600) harvested 49% of the 11-state total of 5,403,300, followed by Tennessee (538,700) and North Carolina (479,900). The margins of error are wide, 12% in Mississippi to 38% in Alabama, and only Arkansas (up 25%) and Mississippi (down 28%) cleared the combined margins of the two seasons. Treat other year-to-year changes as noise rather than as a trend.
Is the duck population down?
The 2026 breeding survey estimated 33.4 million breeding ducks, 6% below the long-term average of 35.4 million. Mallards were 5.9 million, 11% below 2025 and 26% below average, and northern pintails (2.0 million) were 48% below. Breeding numbers are one input to fall flights, and habitat, northern weather and wintering conditions also matter, so the report advises operators to describe conditions as they are and avoid promising bird numbers.
What are the 2026-27 duck limits in the Southeast?
The Atlantic and Mississippi Flyways have the same framework: a season of up to 60 days and a daily bag of 6 ducks, with no more than 4 mallards (no more than two hens), 3 pintails and 3 wood ducks. Redheads, canvasbacks and mottled ducks carry smaller sub-limits, and Louisiana has a new experimental 9-day season for black-bellied whistling ducks at 4 birds a day. States set their own dates, so check current regulations.
How do waterfowl operators compare online with other hunting operators?
They are close to average. Mean digital health for the 139 audited waterfowl operators is 5.32 out of 10, against 5.23 for all audited hunting operators and 5.09 for the Southeast benchmark. Online booking is the weakest point at 5%, the lowest of the eight species tags, and only 1 of 130 sites uses FAQ structured data. Newsletter signup, at 29%, is close to the benchmark's 32.7%. The scan reads homepages only, so every rate is a lower bound.
How big is the audit sample, and is it a census?
It is a sample, not a census. The hunting audit covers 493 businesses, of which 139 carry a waterfowl tag (97 newly verified in October 2026 and 42 from the Southeast audit). Only verified, operating businesses were counted, and groups with fewer than 15 operators are described in words, not percentages. Differences smaller than about 10 percentage points, or half a point of score, are noise, and only Louisiana, Arkansas and Tennessee have enough operators to show separately.
Why is waterfowl often sold alongside other hunts?
Of the 139 audited waterfowl operators, 74 (53%) carry another species tag: 48 are lodges, 34 sell whitetail and 29 sell upland, and 65 sell waterfowl alone. For the website, that means a duck buyer can land on a homepage that is also selling deer, quail and lodging, and has to find the waterfowl page quickly. The report advises giving waterfowl its own page with its own dates, rates and photos.
Can a guide take paying clients on a refuge or wildlife management area?
Only with the managing agency's authorization, and often not at all. In Arkansas, waterfowl guiding is banned on Commission WMAs and on all national wildlife refuges, and in Louisiana paid hunting guiding is barred on WMAs. Mississippi allows no paid guiding on MDWFP WMAs. National forests need a U.S. Forest Service special-use permit, and for any other unit, confirm with the managing agency before you advertise a public-land hunt.
Sources
U.S. Fish and Wildlife Service, Migratory Bird Hunting Activity and Harvest, Harvest Information Program, state estimates for 2023-24 and 2024-25, flyway and national estimates for 2025-26
U.S. Fish and Wildlife Service, Waterfowl Population Status, 2026 May breeding survey
U.S. Fish and Wildlife Service, Wildlife and Sport Fish Restoration Program, certified paid hunting license holders, license years 2020 to 2024
U.S. Bureau of Economic Analysis, Outdoor Recreation Satellite Account, March 2026 release (2024 data)
Pine & Marsh hunting audit, October 2026 (493 operators), and the Pine & Marsh Southeast audit, October 2026 (1,546 operators), used as the benchmark


Comments