
Inside the 2026-27 Outdoor Hospitality Report: State Tables, Lodging Types and Guest Calendars
The 2026-27 Outdoor Hospitality report is the twelfth in our industry series. It covers cabins, glamping, campgrounds, RV parks, rentals and sporting lodges across 11 Southeastern states, and it is built from two sources: public demand data from the Bureau of Economic Analysis (BEA) and ten state tourism reports, and our October 2026 audit of 1,546 outdoor businesses, 84 of which are lodging and campground operators.
It is written for the people who own and market a place to stay near the water, woods or trail. This post walks through the report one chapter at a time. For the overview and the marketing playbook, see Outdoor Hospitality in the Southeast: Cabins, Campgrounds and RV Parks by the Numbers.
At a Glance: Nine Numbers
The opening chapter sets up the report as a large, travel-driven slice of the outdoor economy that is sold mostly through websites that do not yet take a booking. Four of the nine numbers come from BEA and five from the audit.
On the BEA side: U.S. RVing value added of $27.5 billion in 2024, climbing, hiking and tent camping at $7.75 billion, the 11 states' RVing at $5.14 billion, and a statistic that frames the whole report, that 48% of U.S. outdoor recreation value added is supporting spending such as trips, travel and lodging.
On the audit side: 84 lodging and campground operators, a mean digital health score of 5.38 against 5.09 for all audited operators, and three site signals. 10.0% of 70 sites read show a booking engine our scanner detects, 44.3% carry FAQ content and 40.0% offer a newsletter signup.
The summary adds two honest limits that return later. The sample is too thin for state comparisons, since no state has more than 12 audited lodging operators, and the audit sample was built around sporting and outfitter markets, so it is strongest on lodges, resorts and cabins and thinner on campgrounds and RV parks.
Demand: Two Measures of the Same Guests
Outdoor hospitality is not licensed, counted or reported as one industry, so there is no single public number. The chapter works with two families of data and spends real effort keeping them apart. BEA measures value added, the contribution to GDP. State tourism reports measure visitor spending, the gross sales by visitors for every trip purpose. A cabin stay can appear in both, so the report never adds them and never totals visitor spending across states.
The national picture inside BEA is a story of two lines. RVing rose from $22.5 billion in 2019 to $31.2 billion in 2022, then slid to $27.8 billion in 2023 and $27.5 billion in 2024, which is 22% above 2019. Climbing, hiking and tent camping rose from $3.8 billion to $7.75 billion over the same period. Neither line is a revenue figure for campgrounds or lodges, and glamping has no line at all.
The state detail is where the chapter earns its keep.
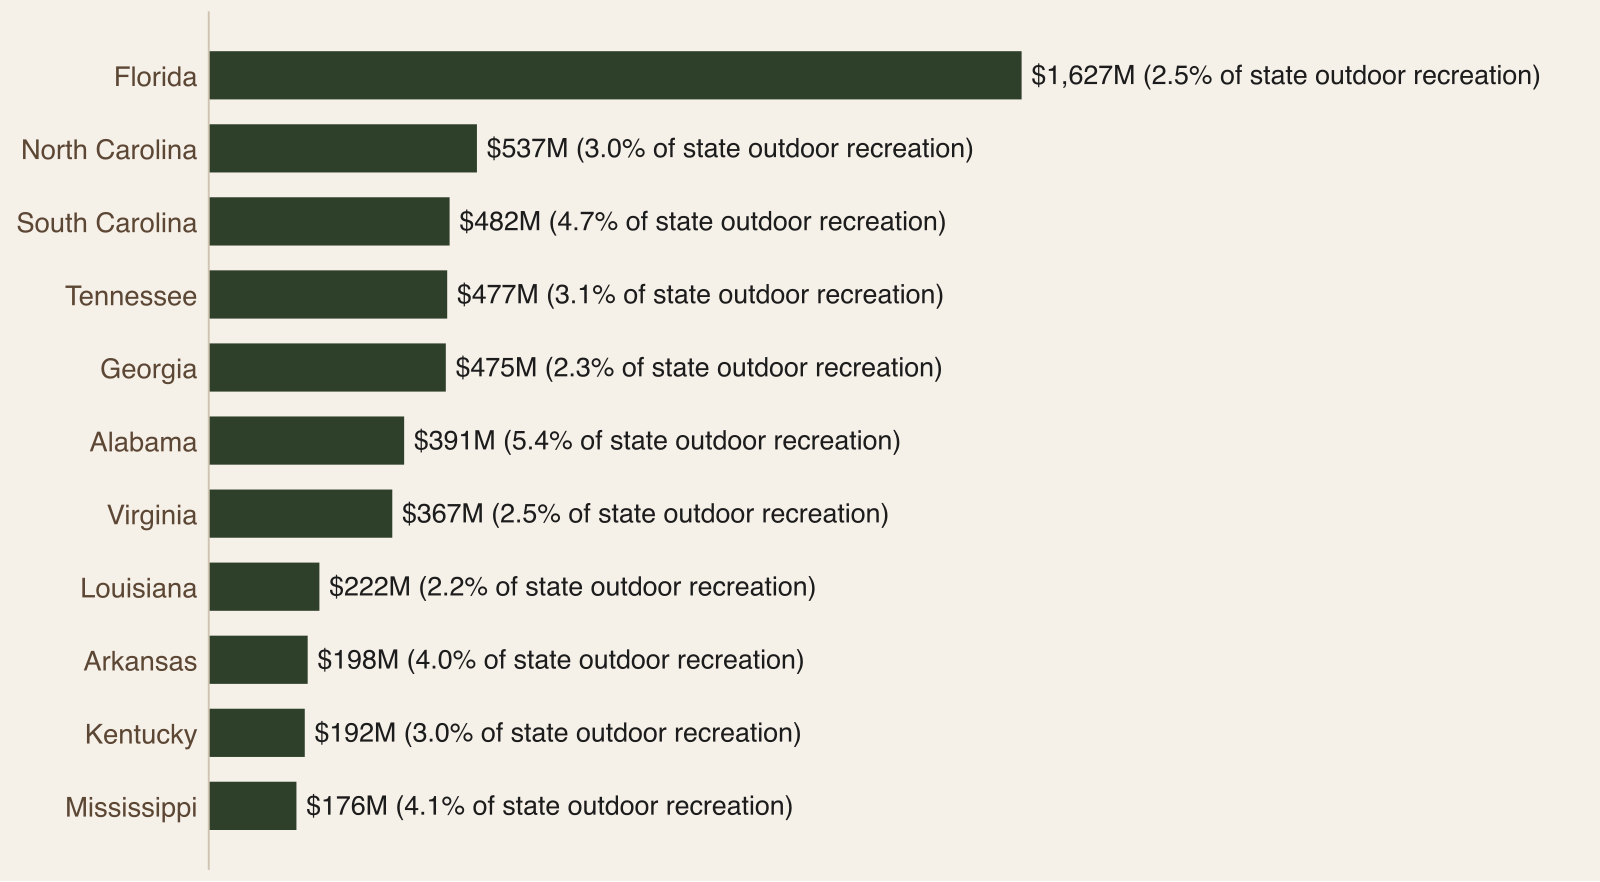
RVing. Florida leads at $1,627 million, followed by North Carolina ($537 million) and South Carolina ($482 million). The line is a bigger share of outdoor recreation in Alabama (5.4%) than in Louisiana (2.2%).
Tent camping, hiking and climbing. State detail is for 2023, from an older BEA release, so it is not used to compute change. The 11 states produced $1,617 million, with Florida at $375 million.
Visitor spending. Ten of the 11 states publish a total, from $10.2 billion in Arkansas to $134.9 billion in Florida. Florida counts out-of-state visitors only, South Carolina counts direct travel spending, North Carolina's is preliminary and Tennessee reports visits, so the chart is a map of scale and not a league table.
Supporting spending. The share runs from 44% in Alabama to 59% in Louisiana, and BEA's accommodation and food services line alone is $97.7 billion nationally. Both include restaurants and other spending, so neither isolates lodging.
The chapter ends on what the data cannot say: no public series counts cabins, glamping units, campground or RV-park sites, or occupancy. Treat these as the pool guests come from, and use your own bookings for your own demand.
Where It Happens
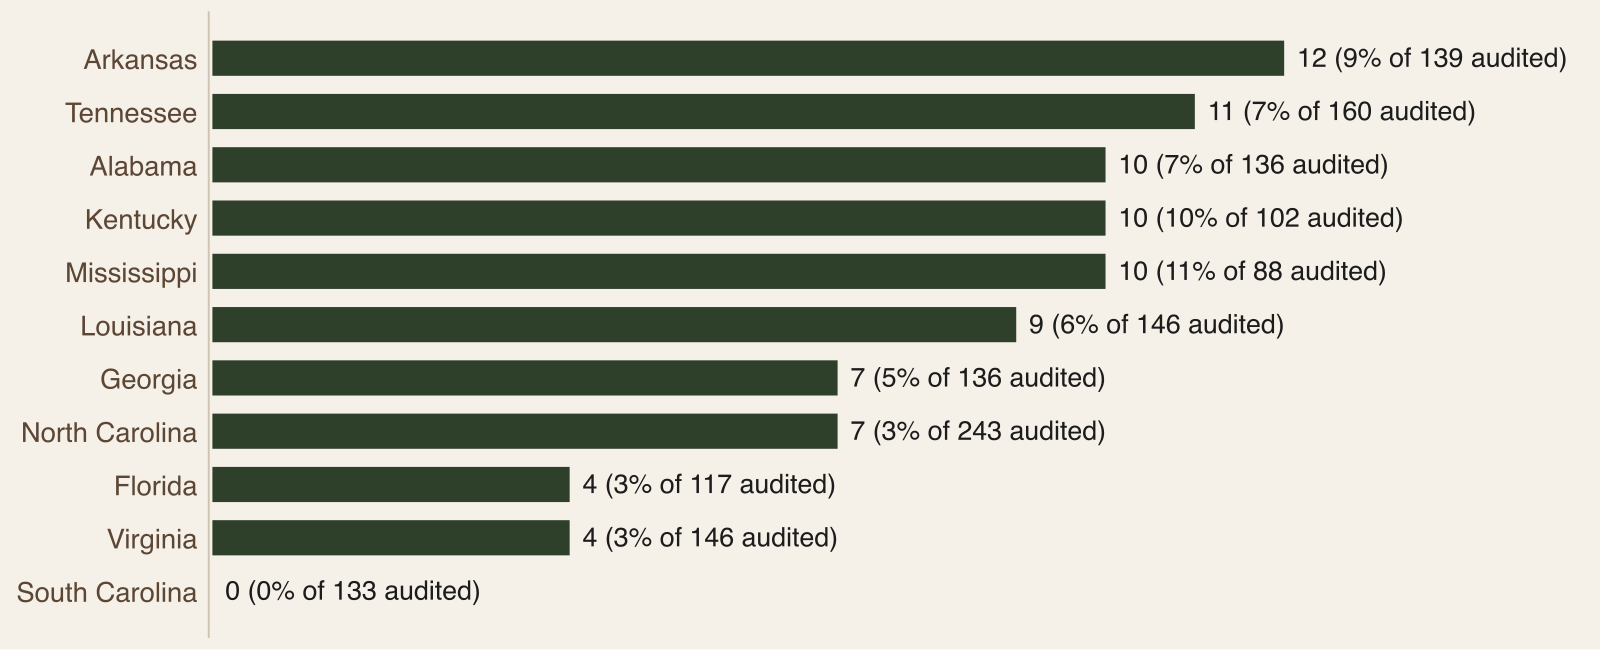
Here the report shifts from public data to the audit. It sampled about 16 operators in each of 97 sub-regions, so the counts show where audited lodging businesses were found, not a census. Arkansas has the most with 12, then Tennessee with 11. Alabama, Kentucky and Mississippi have 10 each, and as a share of each state's audited operators Mississippi (11%) and Kentucky (10%) lean on lodging the most. South Carolina has none, and Florida and Virginia have only 4 each. That reflects how the sample was drawn, not how much lodging those states have.
The state table lines up the audit count against RVing value added, tent camping value added and visitor spending. Read it with the report's two cautions in mind: a state with many audited lodging operators is not necessarily one with a large lodging economy, and the sub-regions were designed around hunting, fishing and outdoor tourism, so coastal resorts, city hotels and campground chains outside them are largely absent.
The group is mostly lodges and cabins. The recorded business types, which are free text and overlap, include lodge (41), cabin (33), resort (20), RV (10) and campground or camping (9). Of the 84, 29 are in the audit's top tier, 30 in the middle and 25 in the lower tier.
The report also groups the 97 sub-regions into five types. Mountains and foothills hold the most audited lodging operators (29, or 35%), then coast and lakes at 16 each, rivers and wetlands at 15 and piedmont and metro interior at 8.
A closing note applies to anyone near public land. Many lodges, cabins and campgrounds sit beside national forests, refuges, wildlife management areas and state parks that regulate commercial use. Guiding there generally requires a permit or authorization from the managing agency, so confirm the rules for each place before selling a trip.
The state table is the chapter's centerpiece, with six columns beside each state: audited lodging operators, their share of the state's audited operators, the number of sub-regions with at least one, RVing value added for 2024, tent camping, hiking and climbing value added for 2023, and visitor spending. Read across a few rows to see why the report cautions against ranking. Arkansas has 12 operators (9%) in 5 of 10 sub-regions, with $198M of RVing, $68M of camping value added and $10.2B of visitor spending. Tennessee has 11 (7%) in 8 of 10 sub-regions, with $477M, $126M and $32.5B. Alabama has 10 (7%) in 4 of 10, Kentucky 10 (10%) in 5 of 10, Mississippi 10 (11%) in 6 of 10 and Louisiana 9 (6%) in 5 of 10.
The large visitor economies sit at the other end of the audit count. Georgia has 7 operators (5%) in 3 of 6 sub-regions against $475M of RVing, $216M of camping value added and $46.2B of visitor spending. North Carolina has 7 (3%) with $537M and $216M. Florida and Virginia have 4 each (3%), with Florida at $1,627M of RVing and $375M of camping, and Virginia at $367M and $172M. South Carolina has none in 0 of 6 sub-regions, against $482M of RVing and $165M of camping value added. In total the 11 states hold 84 audited operators in 45 of 97 sub-regions, against $5,145M of RVing and $1,617M of camping value added. The BEA and visitor-spending columns overlap and are not additive.
The Business Landscape
The audit counts private, for-profit businesses only, so publicly run cabins, campgrounds and park lodges are not in it, though a few privately operated concessions in parks are. The group is 5% of the 1,546 audited and appears in 45 of 97 sub-regions.
The scores are somewhat better than the benchmark. Mean digital health is 5.38 against 5.09, 31.0% score 4 or below against 39.8%, and 17.9% score 8 or above against 12.3%. 91.7% have their own website, against 80.2%.
State scores are not shown because no state has 15 operators. The type-of-place cut is where the report gets specific:
Coast, bays and barrier islands: 5.81 (16 operators)
Mountains and foothills: 5.52 (29 operators)
Lakes and reservoirs: 5.06 (16 operators)
Rivers, deltas and wetlands: 4.87 (15 operators)
Piedmont, plains and metro interior sub-regions hold too few operators to score. The report advises reading the pattern as something to check against your own market and not as a rule.
A useful footnote sits in the methodology. The audit's marina and houseboat rental category (132 operators) was left out because its main product is not a stay. Adding it would pull the combined mean to 5.01 and move FAQ content from above the benchmark to below it, since marinas score lower.
The table by kind of place has more detail than the scores alone. Coast, bays and barrier islands has 16 operators, 94% with their own website, 13 sites read and 25% scoring 4 or below. Mountains and foothills has 29 operators, 93% on their own website, 24 sites read and 34% at 4 or below. Lakes and reservoirs has 16, 81% on their own website, 13 sites read and 38% at 4 or below. Rivers, deltas and wetlands has 15, 93%, 12 sites read and 33% at 4 or below. The sample is structured, with about 16 operators per sub-region across top, middle and lower tiers, so it includes businesses that do not already rank.
The sensitivity table is the methodology footnote in numbers. The lodging and campground group has 84 operators, 70 sites read, a mean of 5.38, 10.0% booking, 44.3% FAQ content and 40.0% newsletter signup. The excluded marina and houseboat rental category has 132 operators, 93 sites read, a mean of 4.78, 11.8% booking, 28.0% FAQ content and 35.5 percent newsletter signup. Both combined would be 216 operators with a mean of 5.01, booking at 11.0%, FAQ content at 35.0% and newsletter signup at 37.4%. The report discloses this as a sensitivity check, not a finding.
How Guests Search and Book
The audit sees a homepage, not a guest, so this chapter pairs measurement with guidance. The guidance is that a guest starts with a place and a kind of stay, then compares a handful of options on whether it fits the group, what a stay includes, whether dates are open, and the cancellation and house rules. Many check third-party listings first, so the operator's own site competes with those listings for the booking.
The measurements come with an important correction. The scanner looks for a short list of tour, activity and appointment booking tools and does not look for lodging property-management systems or campground reservation platforms. Of the 7 sites where it found an engine, 6 use FareHarbor and 1 uses Peek. So the 10.0% is a floor and understates online booking by an amount these data do not show. The report suggests re-scanning with lodging-specific signatures.
The rest of the picture:
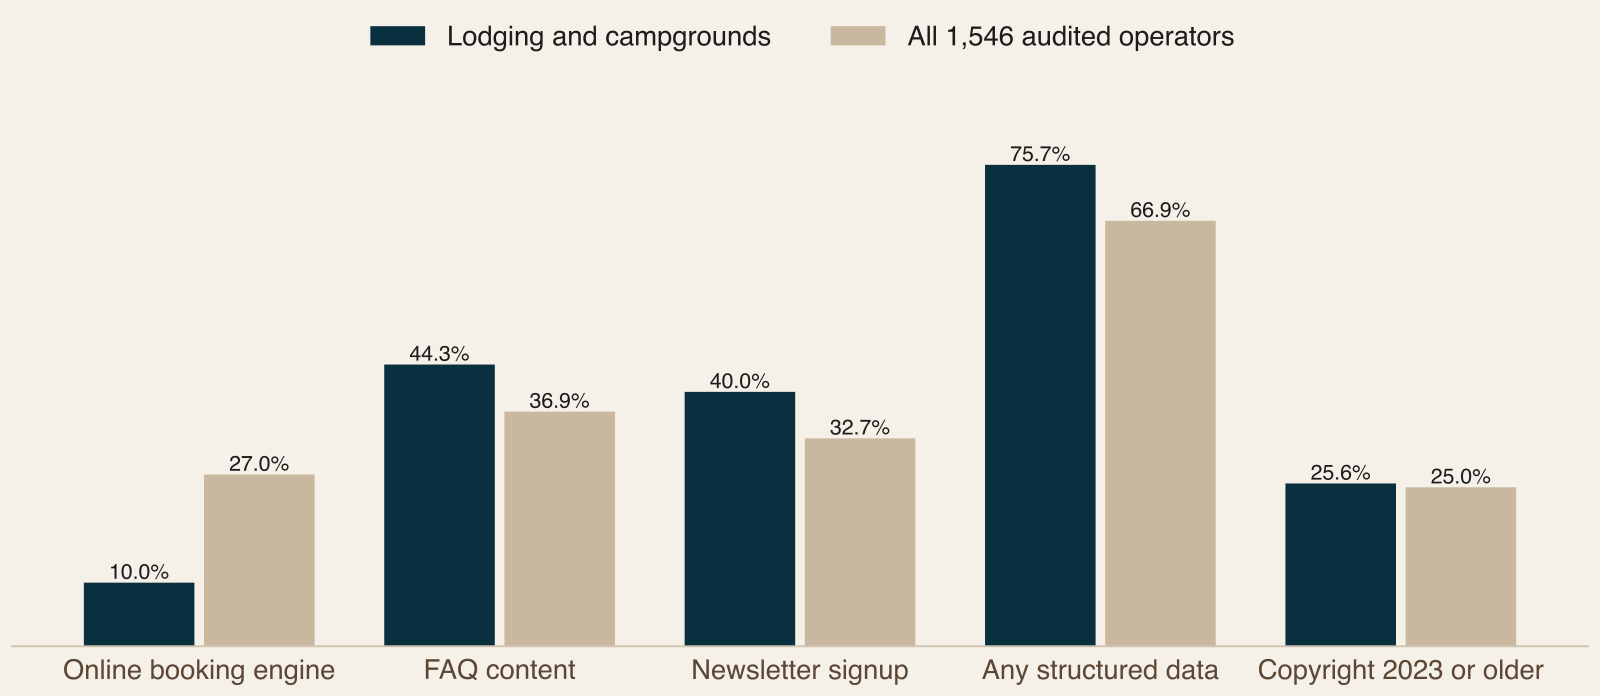
FAQ content is on 44.3% of sites, above the 36.9% benchmark, and FAQ structured data is on 4.3% (3 of 70 sites).
Newsletter signup is 40.0% against 32.7%.
Some structured data appears on 75.7% of sites, usually added by website builders.
25.6% of sites with a detectable copyright year show 2023 or earlier (10 of 39), against 25.0% in the benchmark.
By type of place, booking cells run from 0 to 3 sites and are too small to rank. FAQ content and newsletter signup vary more: FAQ is highest on lakes and reservoirs (61.5%), newsletter highest in the mountains and foothills (54.2%).
The signal table sets lodging against the 1,546-operator benchmark. Booking engines are detected on 7 of 70 lodging sites (10.0%) against 295 of the benchmark's 1,093 (27.0%). FAQ content is 44.3% against 36.9%, FAQ structured data 4.3% against 2.0%, newsletter signup 40.0% against 32.7%, any structured data 75.7% against 66.9% and a copyright year of 2023 or older 25.6% against 25.0%. Across the whole audit the scanner detected FareHarbor on 191 sites, Wix Bookings on 51 and Peek on 38, tools built for tours and activities, which is why a lodging group shows so few.
The by-type table adds the cells behind that last bullet. Booking engines were detected on 1 of 13 coast sites, 3 of 24 in the mountains and foothills, 1 of 13 on lakes and reservoirs and 0 of 12 on rivers. FAQ content runs 46.2% on the coast, 37.5% in the mountains, 61.5% on lakes and 41.7% on rivers, and newsletter signup 30.8%, 54.2%, 23.1% and 41.7%. The report advises reading FAQ and newsletter as the better signals to compare. The practical test it offers is one sentence: from the homepage, can a guest see open dates and reserve in under a minute?
The Year: A General Calendar
This chapter is guidance, not data. It runs five phases: winter planning, spring shoulder season, summer peak, fall foliage and hunting parties, and a quieter off-season. Each phase pairs what guests are doing with what an operator can publish, from posting next season's open dates in winter to promoting midweek stays to the email list in the off-season.
The pattern the report claims is regional: mountain and lake lodging peaks in summer and fall, coastal lodging runs longer, and sporting lodges follow hunting and fishing seasons. A second table maps five kinds of guest to how they book: the weekend family, the camper or RV traveler who checks site size and hookups first, the sporting party booking prime weeks a year ahead, the group needing one invoice, and the repeat guest. The chapter closes with the same four-step exercise used across the series, from listing your dates to writing a storm, flood, low-water and road-closure policy.
The five-phase table is specific about what to publish. In winter, publish next season's open dates, house rules and policies, refresh the homepage year and the FAQ, and test the booking path end to end. In spring, post an opening notice, confirm permits, insurance and inspections, and email last year's guests before the calendar fills. In summer, show live availability, answer messages the same day, publish hookup, pet and boat-parking details and ask every guest for a review. In fall, publish the hunting and fishing calendar you serve, the land you may use and what a stay includes, and say which trips are guided and where. In the off-season, promote midweek and off-season stays to your list, update photos and winter conditions, and collect reviews while stays are fresh.
The four-step exercise is to list your dates, mark your lead times from the last two seasons of reservations, schedule content to lead them, and write the storm, flood, low-water and road-closure policy once. Timing varies by state, elevation, water and product, so the best calendar is your own.
Six Moves for Operators
The six moves are: put a booking path on the homepage, answer guest questions and mark them up, show the stay and not just the property, start a list and use it, keep the site current, and be clear about what is yours and what is public. The suggested starting point is to make the booking path work on a phone, so that the homepage shows what you offer, when you have room and how to reserve in under a minute.
Each of the six moves has a number behind it. Booking: 90% of lodging sites read show no engine the scanner detects (7 of 70). Answers: 44.3% have FAQ content but only 3 of 70 use FAQ structured data. Newsletter: 40.0% against 32.7%. Freshness: 25.6% of sites with a detectable year show 2023 or earlier, which is 10 of 39. The last move, about public land and water, is a reminder to say which trips are guided, by whom, and where.
What It Means for Operators
Three things stand out from reading the chapters in order. The demand data is real but indirect: BEA and tourism reports tell you the pool is large and that camping has outgrown RVing since 2019, and they do not tell you your occupancy. The audit says lodging operators present themselves better than the benchmark and answer guests' questions more often. And the weakest-looking number, booking, is also the one the scanner understates, so check your own booking path before you worry about the 10.0%.
Where the report gives you a number, it also gives you the limit of that number. That is worth borrowing. Date your own claims, say what a figure counts, and your site will read as more trustworthy than a competitor's.
Read the Full Outdoor Hospitality Report
The full report has the state tables, the visitor spending comparison, the type-of-place analysis, the booking and answer signals, the calendar and the sources and methods for every chart.
Download the full 2026-27 Outdoor Hospitality report (free with your email).
Frequently Asked Questions
Does the report say how many cabins, campgrounds or RV parks there are?
No. No public series in the data collected counts cabins, glamping units, campground or RV-park sites, occupancy or revenue, and glamping has no BEA line. The audit group of 84 lodging and campground operators is a verified sample, not a census, and it is strongest on lodges, resorts and cabins. The recorded business types are free text and overlap: lodge (41), cabin (33), resort (20), RV (10) and campground or camping (9). Use your own booking records for your own demand.
Why is RVing described as off its peak while camping is described as growing?
BEA's RVing line peaked at $31.2 billion in 2022 and was $27.5 billion in 2024, 12% below the peak but 22% above 2019. Its climbing, hiking and tent camping line rose from $3.8 billion to $7.75 billion over the same period, a 102% increase. Neither line measures the revenue of a campground or lodge, and the tent camping line also covers climbing and hiking. They are the closest public measures of the demand a camping or RV business draws on.
Can I compare visitor spending between states?
Only as a map of scale. Florida reports out-of-state visitors only, South Carolina reports direct travel spending, North Carolina's figure is preliminary and Tennessee reports visits. The report does not rank the states as like for like and does not total them. Ten of the 11 states publish a total, from $10.2 billion in Arkansas to $134.9 billion in Florida, and visitor spending overlaps with BEA value added, so the two are never added together.
Is the 10.0% online booking rate for lodging a real count?
It is a floor. The scanner matches 12 tour, activity and appointment tools and does not look for lodging property-management systems or campground reservation platforms, so a site that takes reservations through one is not detected. Of the 7 sites where an engine was found, 6 use FareHarbor and 1 uses Peek. The report names re-scanning with lodging-specific signatures as the next step. What the 10.0% does show is that 90% of the sites read show no detectable booking path on the homepage.
Which kinds of lodging place scored best online?
Among the types with enough operators, coast, bays and barrier islands averaged 5.81, mountains and foothills 5.52, lakes and reservoirs 5.06 and rivers, deltas and wetlands 4.87. Piedmont, plains and metro interior had only 8 operators and is not scored. The groupings are broad and judgment-based, and the samples are small, so treat this as a pattern to check against your own market. FAQ content is highest on lakes (61.5%) and newsletter signup highest in the mountains (54.2%).
Why are marinas not counted as lodging in this report?
The audit's marina and houseboat rental category has 132 operators, and its main product is not a stay, so the report leaves it out and discloses the choice. Adding it would give a combined group of 216 operators with a mean of 5.01 instead of 5.38, and would move FAQ content from 44.3% above the benchmark to 35.0%, below it. The sensitivity table is published as a check, not a finding, so a reader can judge the choice.
Why does the report show no state scores for lodging?
No state has the 15 audited lodging operators and 10 sites read that the report requires for a state comparison. The most in any state is 12, in Arkansas, and there are none in South Carolina. State scores are therefore not shown as means or percentages, and the state table is a guide to where the sample found lodging, not a ranking of lodging economies. The audit was built around sporting and outfitter markets, so coastal resorts, city hotels and large campground chains are largely absent.
How should an owner use the report's calendar and guest tables?
Use them as a starting point, not data. The report says the calendar and the guest table are general guidance from Pine & Marsh and that timing varies by state, elevation, water and product. Pull your last two seasons of reservations, note how many days ahead each kind of guest booked, and schedule your content to lead them. Weekend families plan weeks ahead, sporting parties book prime weeks up to a year ahead, and groups want one invoice, but your own records are the test.
Sources
U.S. Bureau of Economic Analysis, Outdoor Recreation Satellite Account, March 2026 release (2019 to 2024) and November 2024 release (2023 state data)
State tourism economic-impact reports for Alabama, Arkansas, Georgia, Kentucky, Louisiana, Mississippi, North Carolina, Tennessee and Virginia (2025 editions) and Florida and South Carolina (2024 editions)
Pine & Marsh Southeast audit, October 2026 (1,546 operators in 97 sub-regions, 84 in the Lodging and Campgrounds category)


Comments